
The efficiency of your company’s treasury depends on data accuracy. In the Mexican financial ecosystem, the CLABE (Standardized Bank Code) is the unique identifier that allows your funds to move through the SPEI (Interbank Electronic Payment System) immediately and without errors.
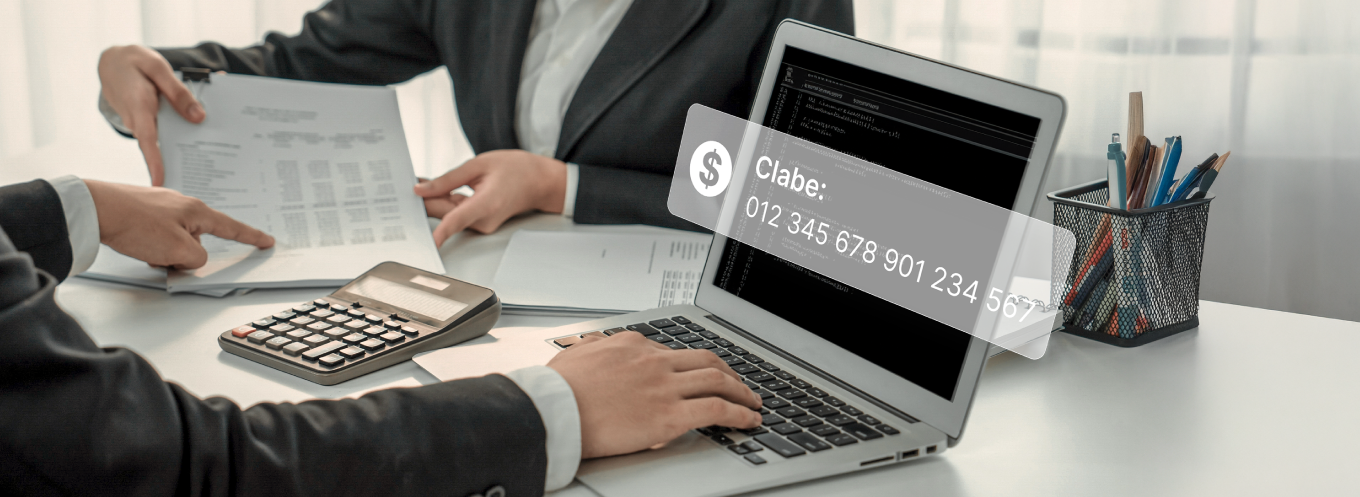
The CLABE is a unique 18-digit number assigned to every bank account in Mexico. It was created by the Mexican Banking Association in collaboration with Banxico in 2004 to standardize transfers between different banks and enable the SPEI.
The primary function of the CLABE is to ensure that fund transfers between different financial institutions are directed to the correct destination, eliminating the ambiguity that could arise from using only the card number or local account number.
The 18 digits of the CLABE are standardized into four parts: 3 digits for the bank, 3 for the city, 11 for the account number, and 1 check digit.
In the corporate environment, the CLABE goes beyond simply sending money; it is a tool for reconciliation and visibility. Some of its operational uses include:
Yes, the CLABE is designed using security protocols that protect the integrity of your funds. Since it is a read-only code for transfers, sharing it does not grant third parties permission to withdraw funds or make automatic charges to your account.
To ensure your B2B payments reach the correct supplier, you can validate the information in the following ways:
Modern payment infrastructures, such as Cobre, validate CLABE numbers directly with banks in real time. This detects errors before processing, preventing funds from being sent to incorrect or nonexistent accounts.
Yes. Companies with complex operations use multiple CLABEs for better control of their operations:
Some banks allow you to create CLABE subaccounts linked to a main account, each with a unique 18-digit number but linked for accounting purposes.
However, the number of bank accounts you can open is usually limited. This is where virtual CLABEs come in: valid collection references within SPEI that are linked to the same account or balance, allowing you to scale your collections without opening multiple bank accounts.
Virtual CLABEs are SPEI-compatible payment identifiers that function as references linked to a main balance in MXN. Instead of opening a bank account for each customer or transaction, you can generate multiple virtual CLABEs linked to a single centralized balance.
How does it work? Your company shares a virtual CLABE with each customer or for each invoice. When the customer makes an SPEI transfer to that virtual CLABE, the funds are automatically credited to the main balance. The transaction includes metadata that identifies exactly which virtual CLABE received the payment, enabling accurate reconciliation without manual intervention.
Typical use cases: Assign a virtual CLABE per customer to automatically identify payments, one per invoice to reconcile collections at the document level, or one per business line to segment operating revenue.
Operational control: Virtual CLABEs have a simple lifecycle (enabled or disabled). If you need to stop receiving payments under a specific reference, you deactivate it, and transfers sent to that CLABE are automatically rejected, without affecting the main account or other active references.
This model transforms a single account into a multi-reference collection point for Mexico, ideal for high-volume operations that require clear traceability between incoming payments and internal records.
When your company works with different banks, manually managing tokens and portals becomes inefficient. The solution is to use a financial orchestration infrastructure that centralizes your operations.
If your finance team spends hours processing payments across multiple banking portals and then even more time reconciling accounts, Cobre has the solution.
With Cross Border Payments, you can scale your payroll disbursement or supplier payment operations in Mexico thanks to a direct connection with SPEI. Cobre uses counterparties such as the interbank CLABE for transfers, as well as virtual CLABEs for scalable collections.
Additionally, with Cobre Connect, reconciliation goes from being a manual and laborious task to an automated, unified process on a single platform. A tool for connecting your accounts across different banks, providing visibility and treasury management, as well as payment orchestration.
The bank account number is used for internal transactions within the same bank. It consists of 8 to 12 digits and is usually found on the back of debit cards.
The CLABE is a universal identifier for payments between banks. It always has exactly 18 digits and is required for transactions via SPEI.
If you use SPEI, the money arrives in less than 10 seconds. This speed is what sets Mexico apart from other markets where transfers between banks still take days.
If you have an account with a Mexican bank, you can find your CLABE on the first page of your account statement, in your online banking portal, or in your account details within the banking app. You can also call your bank.
If you have a business checking account, you’ll find your 18-digit CLABE there.
Yes, the CLABE is required to receive money from abroad.
When someone makes an international transfer via SWIFT, after the transactions are processed by the bank where the funds are withdrawn and the intermediary banks, the money arrives at a Mexican bank that converts the funds to MXN and deposits them, via SPEI, to the destination CLABE.
This process takes 2–5 business days. To receive the funds, you need to provide your CLABE and the SWIFT code of your company’s Mexican bank.
Each bank account has its own unique CLABE. If your company has an account at BBVA and another at Santander, each one has a different CLABE.
Make sure it has exactly 18 digits. The last digit is a check digit that mathematically validates the entire structure. If something is wrong (a number swapped, a digit missing or extra), the check digit won’t match. Modern financial service platforms validate this automatically before processing.
Contact the recipient immediately, before they send the money. Once the money has been sent to the wrong CLABE, recovering it requires paperwork with both banks, can take weeks, and isn’t always possible. That’s why companies that process bulk payments implement double validation before disbursement.
Yes. When you authorize recurring charges (insurance, tuition, utilities), you provide your CLABE so the provider can automatically withdraw funds. Unlike receiving payments, here you are authorizing withdrawals.
Read the terms carefully before setting up a direct debit.
The efficiency of your company’s treasury depends on data accuracy. In the Mexican financial ecosystem, the CLABE (Standardized Bank Code) is the unique identifier that allows your funds to move through the SPEI (Interbank Electronic Payment System) immediately and without errors.
The CLABE is a unique 18-digit number assigned to every bank account in Mexico. It was created by the Mexican Banking Association in collaboration with Banxico in 2004 to standardize transfers between different banks and enable the SPEI.
The primary function of the CLABE is to ensure that fund transfers between different financial institutions are directed to the correct destination, eliminating the ambiguity that could arise from using only the card number or local account number.
The 18 digits of the CLABE are standardized into four parts: 3 digits for the bank, 3 for the city, 11 for the account number, and 1 check digit.
In the corporate environment, the CLABE goes beyond simply sending money; it is a tool for reconciliation and visibility. Some of its operational uses include:
Yes, the CLABE is designed using security protocols that protect the integrity of your funds. Since it is a read-only code for transfers, sharing it does not grant third parties permission to withdraw funds or make automatic charges to your account.
To ensure your B2B payments reach the correct supplier, you can validate the information in the following ways:
Modern payment infrastructures, such as Cobre, validate CLABE numbers directly with banks in real time. This detects errors before processing, preventing funds from being sent to incorrect or nonexistent accounts.
Yes. Companies with complex operations use multiple CLABEs for better control of their operations:
Some banks allow you to create CLABE subaccounts linked to a main account, each with a unique 18-digit number but linked for accounting purposes.
However, the number of bank accounts you can open is usually limited. This is where virtual CLABEs come in: valid collection references within SPEI that are linked to the same account or balance, allowing you to scale your collections without opening multiple bank accounts.
Virtual CLABEs are SPEI-compatible payment identifiers that function as references linked to a main balance in MXN. Instead of opening a bank account for each customer or transaction, you can generate multiple virtual CLABEs linked to a single centralized balance.
How does it work? Your company shares a virtual CLABE with each customer or for each invoice. When the customer makes an SPEI transfer to that virtual CLABE, the funds are automatically credited to the main balance. The transaction includes metadata that identifies exactly which virtual CLABE received the payment, enabling accurate reconciliation without manual intervention.
Typical use cases: Assign a virtual CLABE per customer to automatically identify payments, one per invoice to reconcile collections at the document level, or one per business line to segment operating revenue.
Operational control: Virtual CLABEs have a simple lifecycle (enabled or disabled). If you need to stop receiving payments under a specific reference, you deactivate it, and transfers sent to that CLABE are automatically rejected, without affecting the main account or other active references.
This model transforms a single account into a multi-reference collection point for Mexico, ideal for high-volume operations that require clear traceability between incoming payments and internal records.
When your company works with different banks, manually managing tokens and portals becomes inefficient. The solution is to use a financial orchestration infrastructure that centralizes your operations.
If your finance team spends hours processing payments across multiple banking portals and then even more time reconciling accounts, Cobre has the solution.
With Cross Border Payments, you can scale your payroll disbursement or supplier payment operations in Mexico thanks to a direct connection with SPEI. Cobre uses counterparties such as the interbank CLABE for transfers, as well as virtual CLABEs for scalable collections.
Additionally, with Cobre Connect, reconciliation goes from being a manual and laborious task to an automated, unified process on a single platform. A tool for connecting your accounts across different banks, providing visibility and treasury management, as well as payment orchestration.
The bank account number is used for internal transactions within the same bank. It consists of 8 to 12 digits and is usually found on the back of debit cards.
The CLABE is a universal identifier for payments between banks. It always has exactly 18 digits and is required for transactions via SPEI.
If you use SPEI, the money arrives in less than 10 seconds. This speed is what sets Mexico apart from other markets where transfers between banks still take days.
If you have an account with a Mexican bank, you can find your CLABE on the first page of your account statement, in your online banking portal, or in your account details within the banking app. You can also call your bank.
If you have a business checking account, you’ll find your 18-digit CLABE there.
Yes, the CLABE is required to receive money from abroad.
When someone makes an international transfer via SWIFT, after the transactions are processed by the bank where the funds are withdrawn and the intermediary banks, the money arrives at a Mexican bank that converts the funds to MXN and deposits them, via SPEI, to the destination CLABE.
This process takes 2–5 business days. To receive the funds, you need to provide your CLABE and the SWIFT code of your company’s Mexican bank.
Each bank account has its own unique CLABE. If your company has an account at BBVA and another at Santander, each one has a different CLABE.
Make sure it has exactly 18 digits. The last digit is a check digit that mathematically validates the entire structure. If something is wrong (a number swapped, a digit missing or extra), the check digit won’t match. Modern financial service platforms validate this automatically before processing.
Contact the recipient immediately, before they send the money. Once the money has been sent to the wrong CLABE, recovering it requires paperwork with both banks, can take weeks, and isn’t always possible. That’s why companies that process bulk payments implement double validation before disbursement.
Yes. When you authorize recurring charges (insurance, tuition, utilities), you provide your CLABE so the provider can automatically withdraw funds. Unlike receiving payments, here you are authorizing withdrawals.
Read the terms carefully before setting up a direct debit.