
A bank layout is a template used by financial institutions to identify account information and transaction details.
Having a bank or payroll layout is necessary for three main reasons: to standardize data capture according to the financial institution’s technical parameters, to integrate automatic validation processes that eliminate manual data entry, and to centralize multi-bank operations in a single interface.
An optimized layout structure allows for the accurate processing of bulk transactions, reducing reconciliation times and mitigating the risk of operational rejections.
However, achieving this level of technical efficiency requires certain measures:
In this article, we explain the techniques and strategies for tackling the challenge of bank reconciliation and payroll distribution.
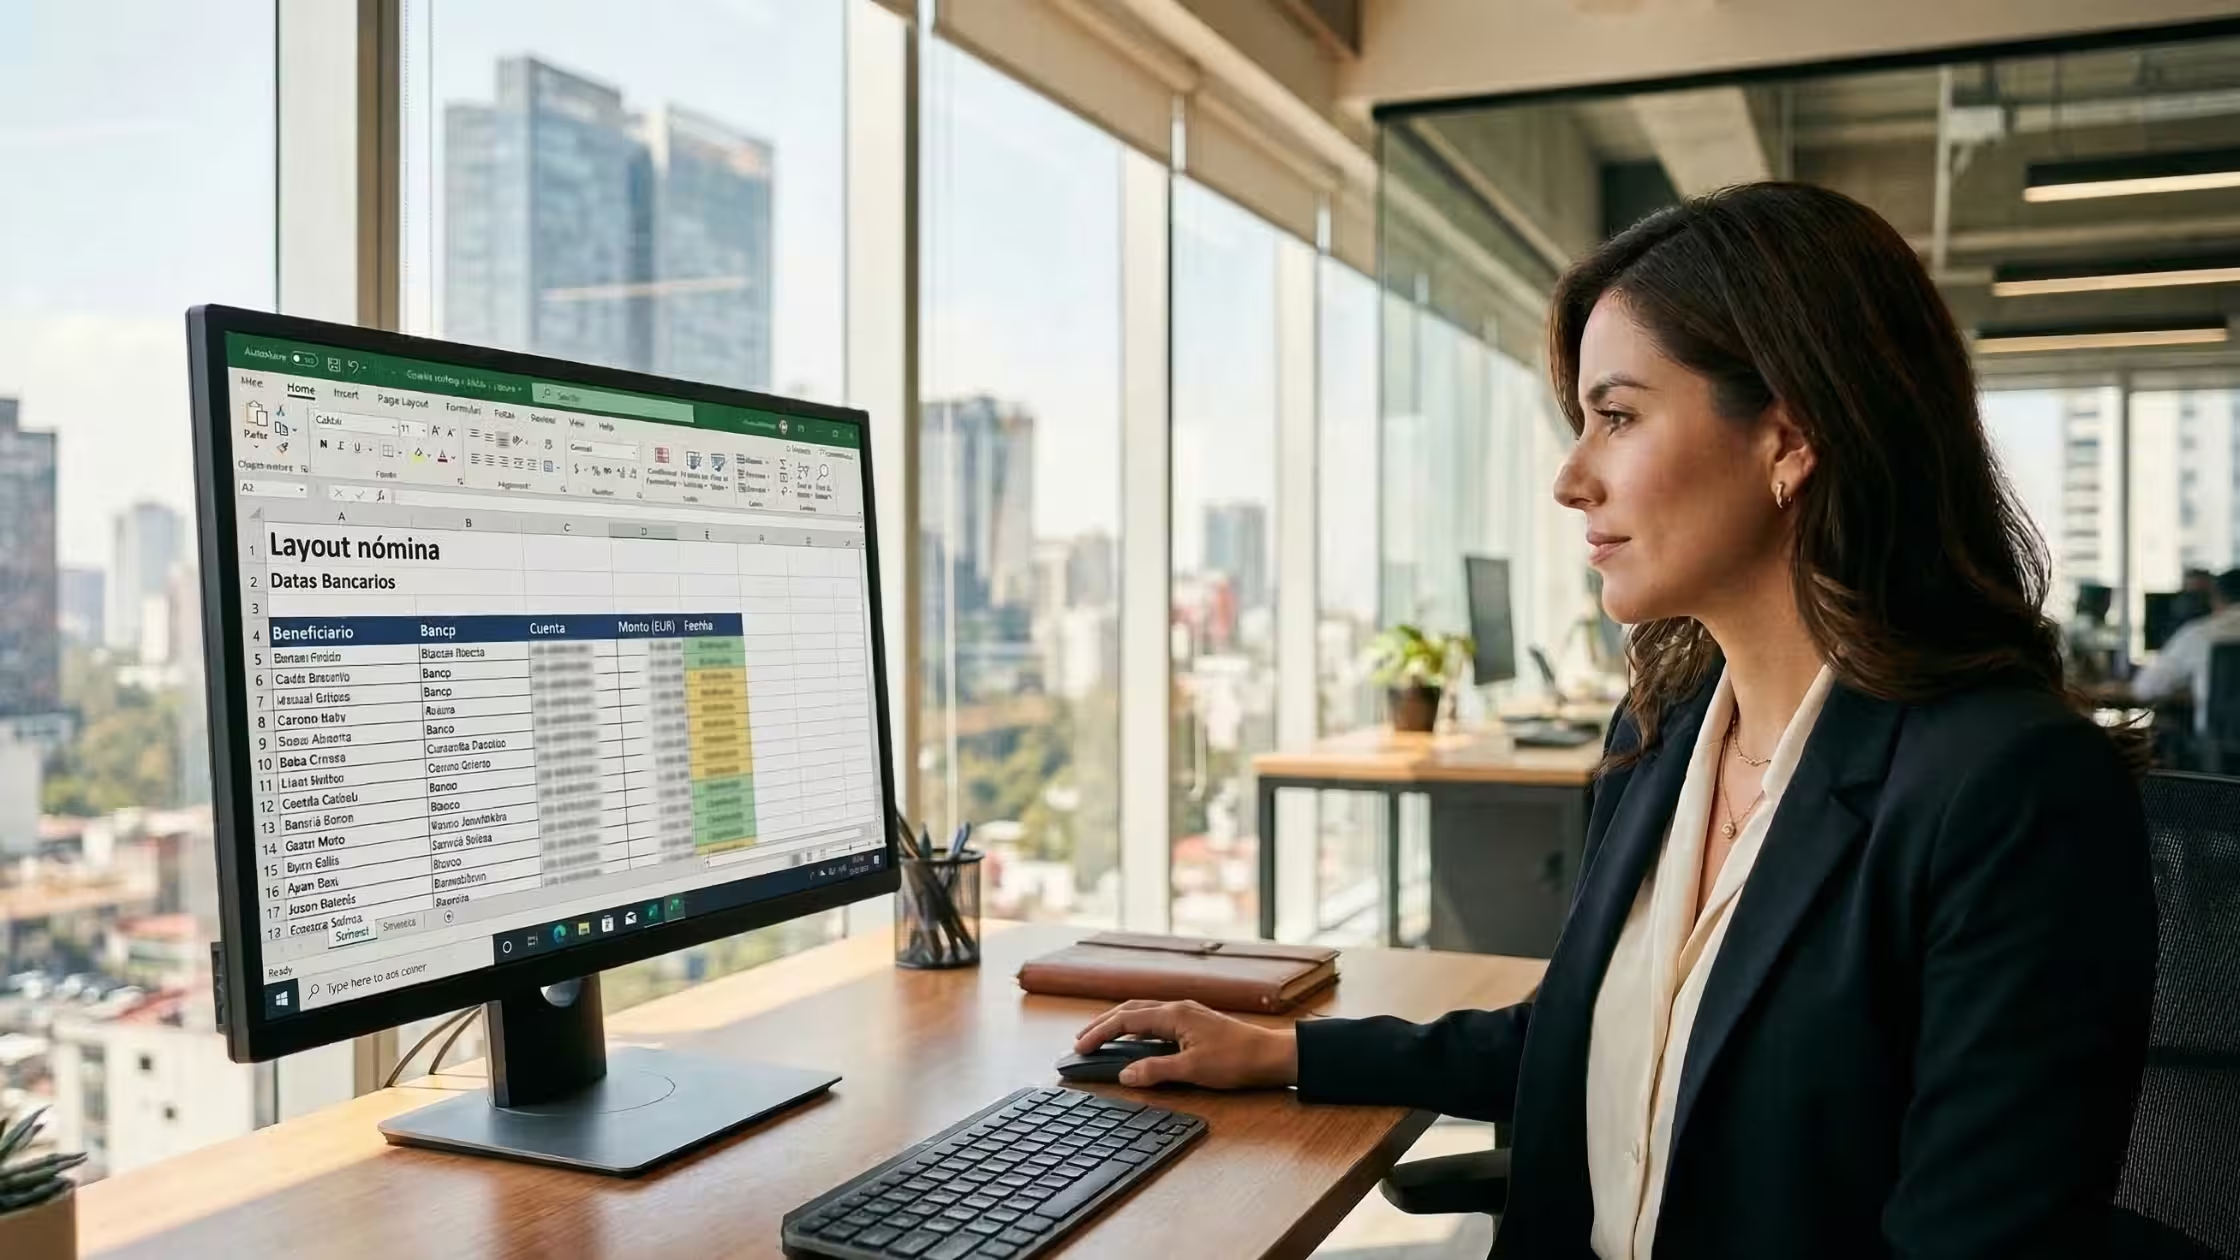
A bank layout is a text or data file (usually in .txt, .csv, or .xlsx format) that contains a technical structure predefined by a financial institution. Its purpose is to standardize the information required to execute bulk payment transactions, such as payments to suppliers or payroll disbursements.
For a layout to be processable and avoid bank rejections, it must contain mandatory fields that the bank’s system automatically validates. These fields typically include:
Depending on operational needs and the financial institution, there are different structures:
Having an optimized layout is the difference between a treasury stuck in manual processes and a scalable operation.
A poorly structured layout is the main cause of failures in bulk payment distribution. A missing digit or a misplaced space can halt the cash flow of hundreds of beneficiaries, leading to operational reprocessing and administrative friction.
To optimize a layout, it is essential to consider the following: use the appropriate technical format, identify the mandatory fields for each institution, and confirm regulatory compliance.
The first step is to determine the format (.txt, .csv, .xml) that best suits both your accounting system’s export capabilities and the receiving bank’s processing requirements.
The correct format ensures that the information is organized without any loss of integrity during the transfer.
Each financial institution has specific protocols depending on the type of payment (payroll, interbank payments, or benefits). It is imperative to request and strictly follow the bank’s technical instructions to avoid mass rejections due to data inconsistencies.
In Colombia, the structure of payment distribution is typically based on payroll and interbank payment requirements, where data such as the financial institution’s code and account type (savings or checking) must be validated.
In Mexico, payroll disbursement is governed by portability processes and requires precise validation by the receiving bank to ensure that funds are delivered correctly through systems such as SPEI.
It is the responsibility of the finance department to verify that the layout complies with all applicable legal regulations and security standards in the jurisdiction of operation (such as the regulations of the SFC in Colombia or Banxico in Mexico).
Although the bank layout is used for automating disbursements, periodic audits must be conducted to ensure that the payment structure remains compliant with regulatory updates.
Yes, manual intervention in the creation of layouts is the primary source of operational errors, but integrating multi-bank automation and centralization tools with infrastructures like Cobre helps mitigate risks, ensure data accuracy, and free the treasury team from repetitive, low-value-added tasks.
The value of this automation lies in the scalability of your operation.
Traditionally, companies that operate with multiple banks must manage a unique layout for each institution. This not only increases technical complexity but also drives up costs, as many banks offer reconciliation services as a value-added service at an extra cost.
When operating with different banks in a fragmented manner, operating costs rise and efficiency drops dramatically.
In Colombia, moreover, the cost of multi-bank operations increases when considering the impact of the GMF (4x1000) tax on money transfers.
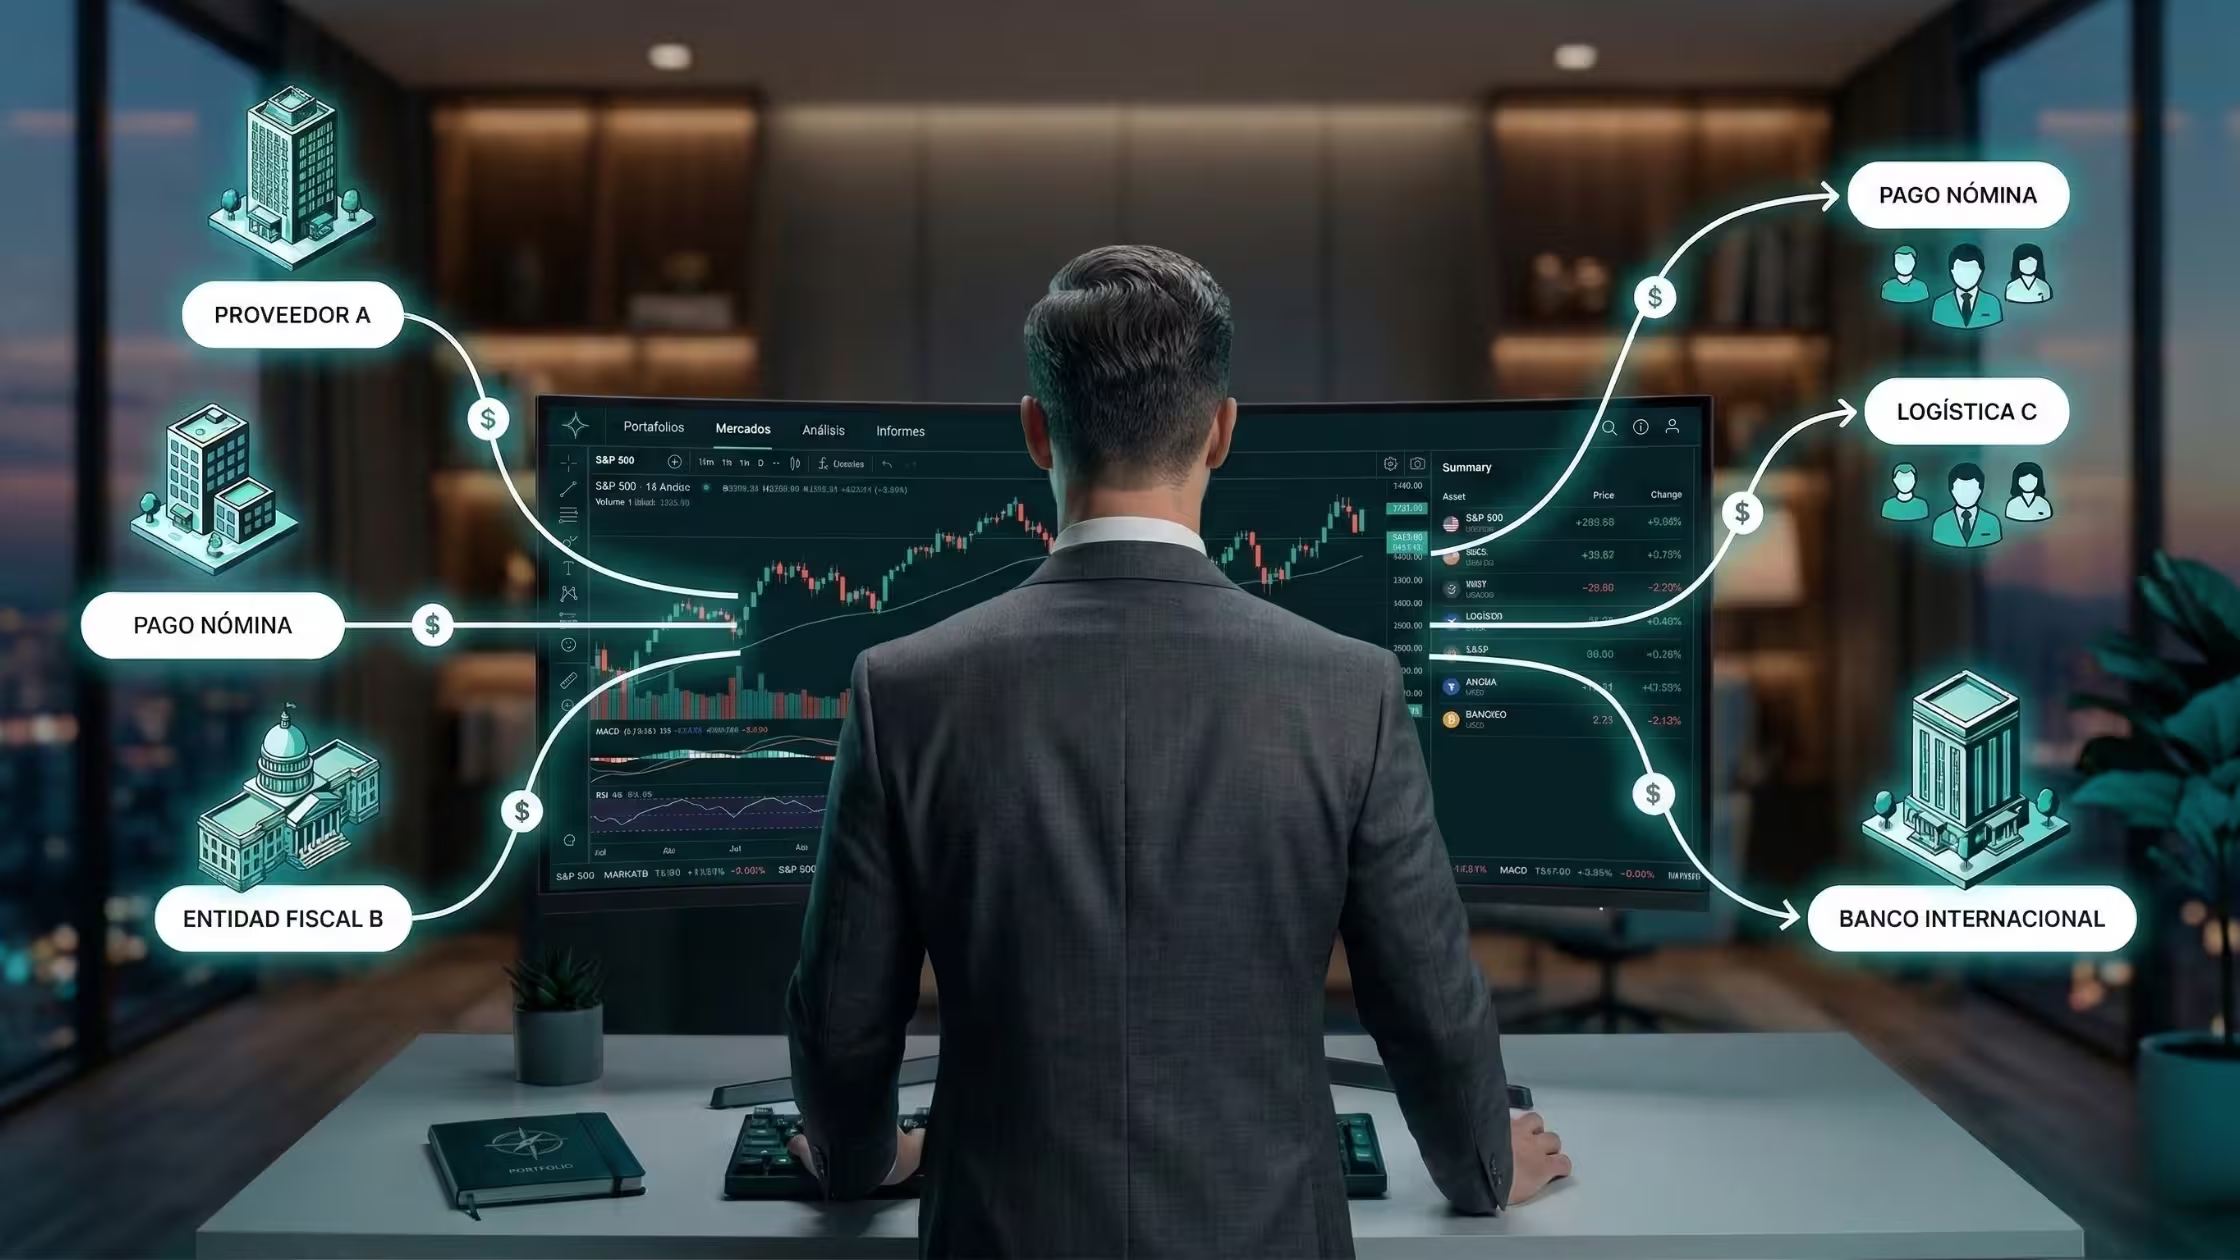
Cobre solves this challenge—for both Colombian companies and those in other Latin American countries—through centralization. Our platform for interbank payments enables companies to:
Centralize your operations, automate your disbursements, and gain full visibility into your cash flow with Cobre’s financial infrastructure.
A bank layout is a template used by financial institutions to identify account information and transaction details.
Having a bank or payroll layout is necessary for three main reasons: to standardize data capture according to the financial institution’s technical parameters, to integrate automatic validation processes that eliminate manual data entry, and to centralize multi-bank operations in a single interface.
An optimized layout structure allows for the accurate processing of bulk transactions, reducing reconciliation times and mitigating the risk of operational rejections.
However, achieving this level of technical efficiency requires certain measures:
In this article, we explain the techniques and strategies for tackling the challenge of bank reconciliation and payroll distribution.
A bank layout is a text or data file (usually in .txt, .csv, or .xlsx format) that contains a technical structure predefined by a financial institution. Its purpose is to standardize the information required to execute bulk payment transactions, such as payments to suppliers or payroll disbursements.
For a layout to be processable and avoid bank rejections, it must contain mandatory fields that the bank’s system automatically validates. These fields typically include:
Depending on operational needs and the financial institution, there are different structures:
Having an optimized layout is the difference between a treasury stuck in manual processes and a scalable operation.
A poorly structured layout is the main cause of failures in bulk payment distribution. A missing digit or a misplaced space can halt the cash flow of hundreds of beneficiaries, leading to operational reprocessing and administrative friction.
To optimize a layout, it is essential to consider the following: use the appropriate technical format, identify the mandatory fields for each institution, and confirm regulatory compliance.
The first step is to determine the format (.txt, .csv, .xml) that best suits both your accounting system’s export capabilities and the receiving bank’s processing requirements.
The correct format ensures that the information is organized without any loss of integrity during the transfer.
Each financial institution has specific protocols depending on the type of payment (payroll, interbank payments, or benefits). It is imperative to request and strictly follow the bank’s technical instructions to avoid mass rejections due to data inconsistencies.
In Colombia, the structure of payment distribution is typically based on payroll and interbank payment requirements, where data such as the financial institution’s code and account type (savings or checking) must be validated.
In Mexico, payroll disbursement is governed by portability processes and requires precise validation by the receiving bank to ensure that funds are delivered correctly through systems such as SPEI.
It is the responsibility of the finance department to verify that the layout complies with all applicable legal regulations and security standards in the jurisdiction of operation (such as the regulations of the SFC in Colombia or Banxico in Mexico).
Although the bank layout is used for automating disbursements, periodic audits must be conducted to ensure that the payment structure remains compliant with regulatory updates.
Yes, manual intervention in the creation of layouts is the primary source of operational errors, but integrating multi-bank automation and centralization tools with infrastructures like Cobre helps mitigate risks, ensure data accuracy, and free the treasury team from repetitive, low-value-added tasks.
The value of this automation lies in the scalability of your operation.
Traditionally, companies that operate with multiple banks must manage a unique layout for each institution. This not only increases technical complexity but also drives up costs, as many banks offer reconciliation services as a value-added service at an extra cost.
When operating with different banks in a fragmented manner, operating costs rise and efficiency drops dramatically.
In Colombia, moreover, the cost of multi-bank operations increases when considering the impact of the GMF (4x1000) tax on money transfers.
Cobre solves this challenge—for both Colombian companies and those in other Latin American countries—through centralization. Our platform for interbank payments enables companies to:
Centralize your operations, automate your disbursements, and gain full visibility into your cash flow with Cobre’s financial infrastructure.