Blog

Off-ramp: how Cobre solves the last mile for stablecoin payments

Reading of
0
minutes
The true leverage of stablecoin payments relies on their off-ramp movement: disbursing in local fiat and reaching their destined wallets.

In this article

Key takeaways

  • The off-ramp is the payment. A stablecoin transfer is settled when local currency reaches the beneficiary's bank, not when the chain confirms it.
  • US multi-rail stops at the border. Delivery inside Mexico and Colombia requires direct connectivity to SPEI, Bre-B, and Fast Pay.
  • One platform, one ledger. Off-ramp, local payouts, and reconciliation run from a single API and dashboard under the same controls.

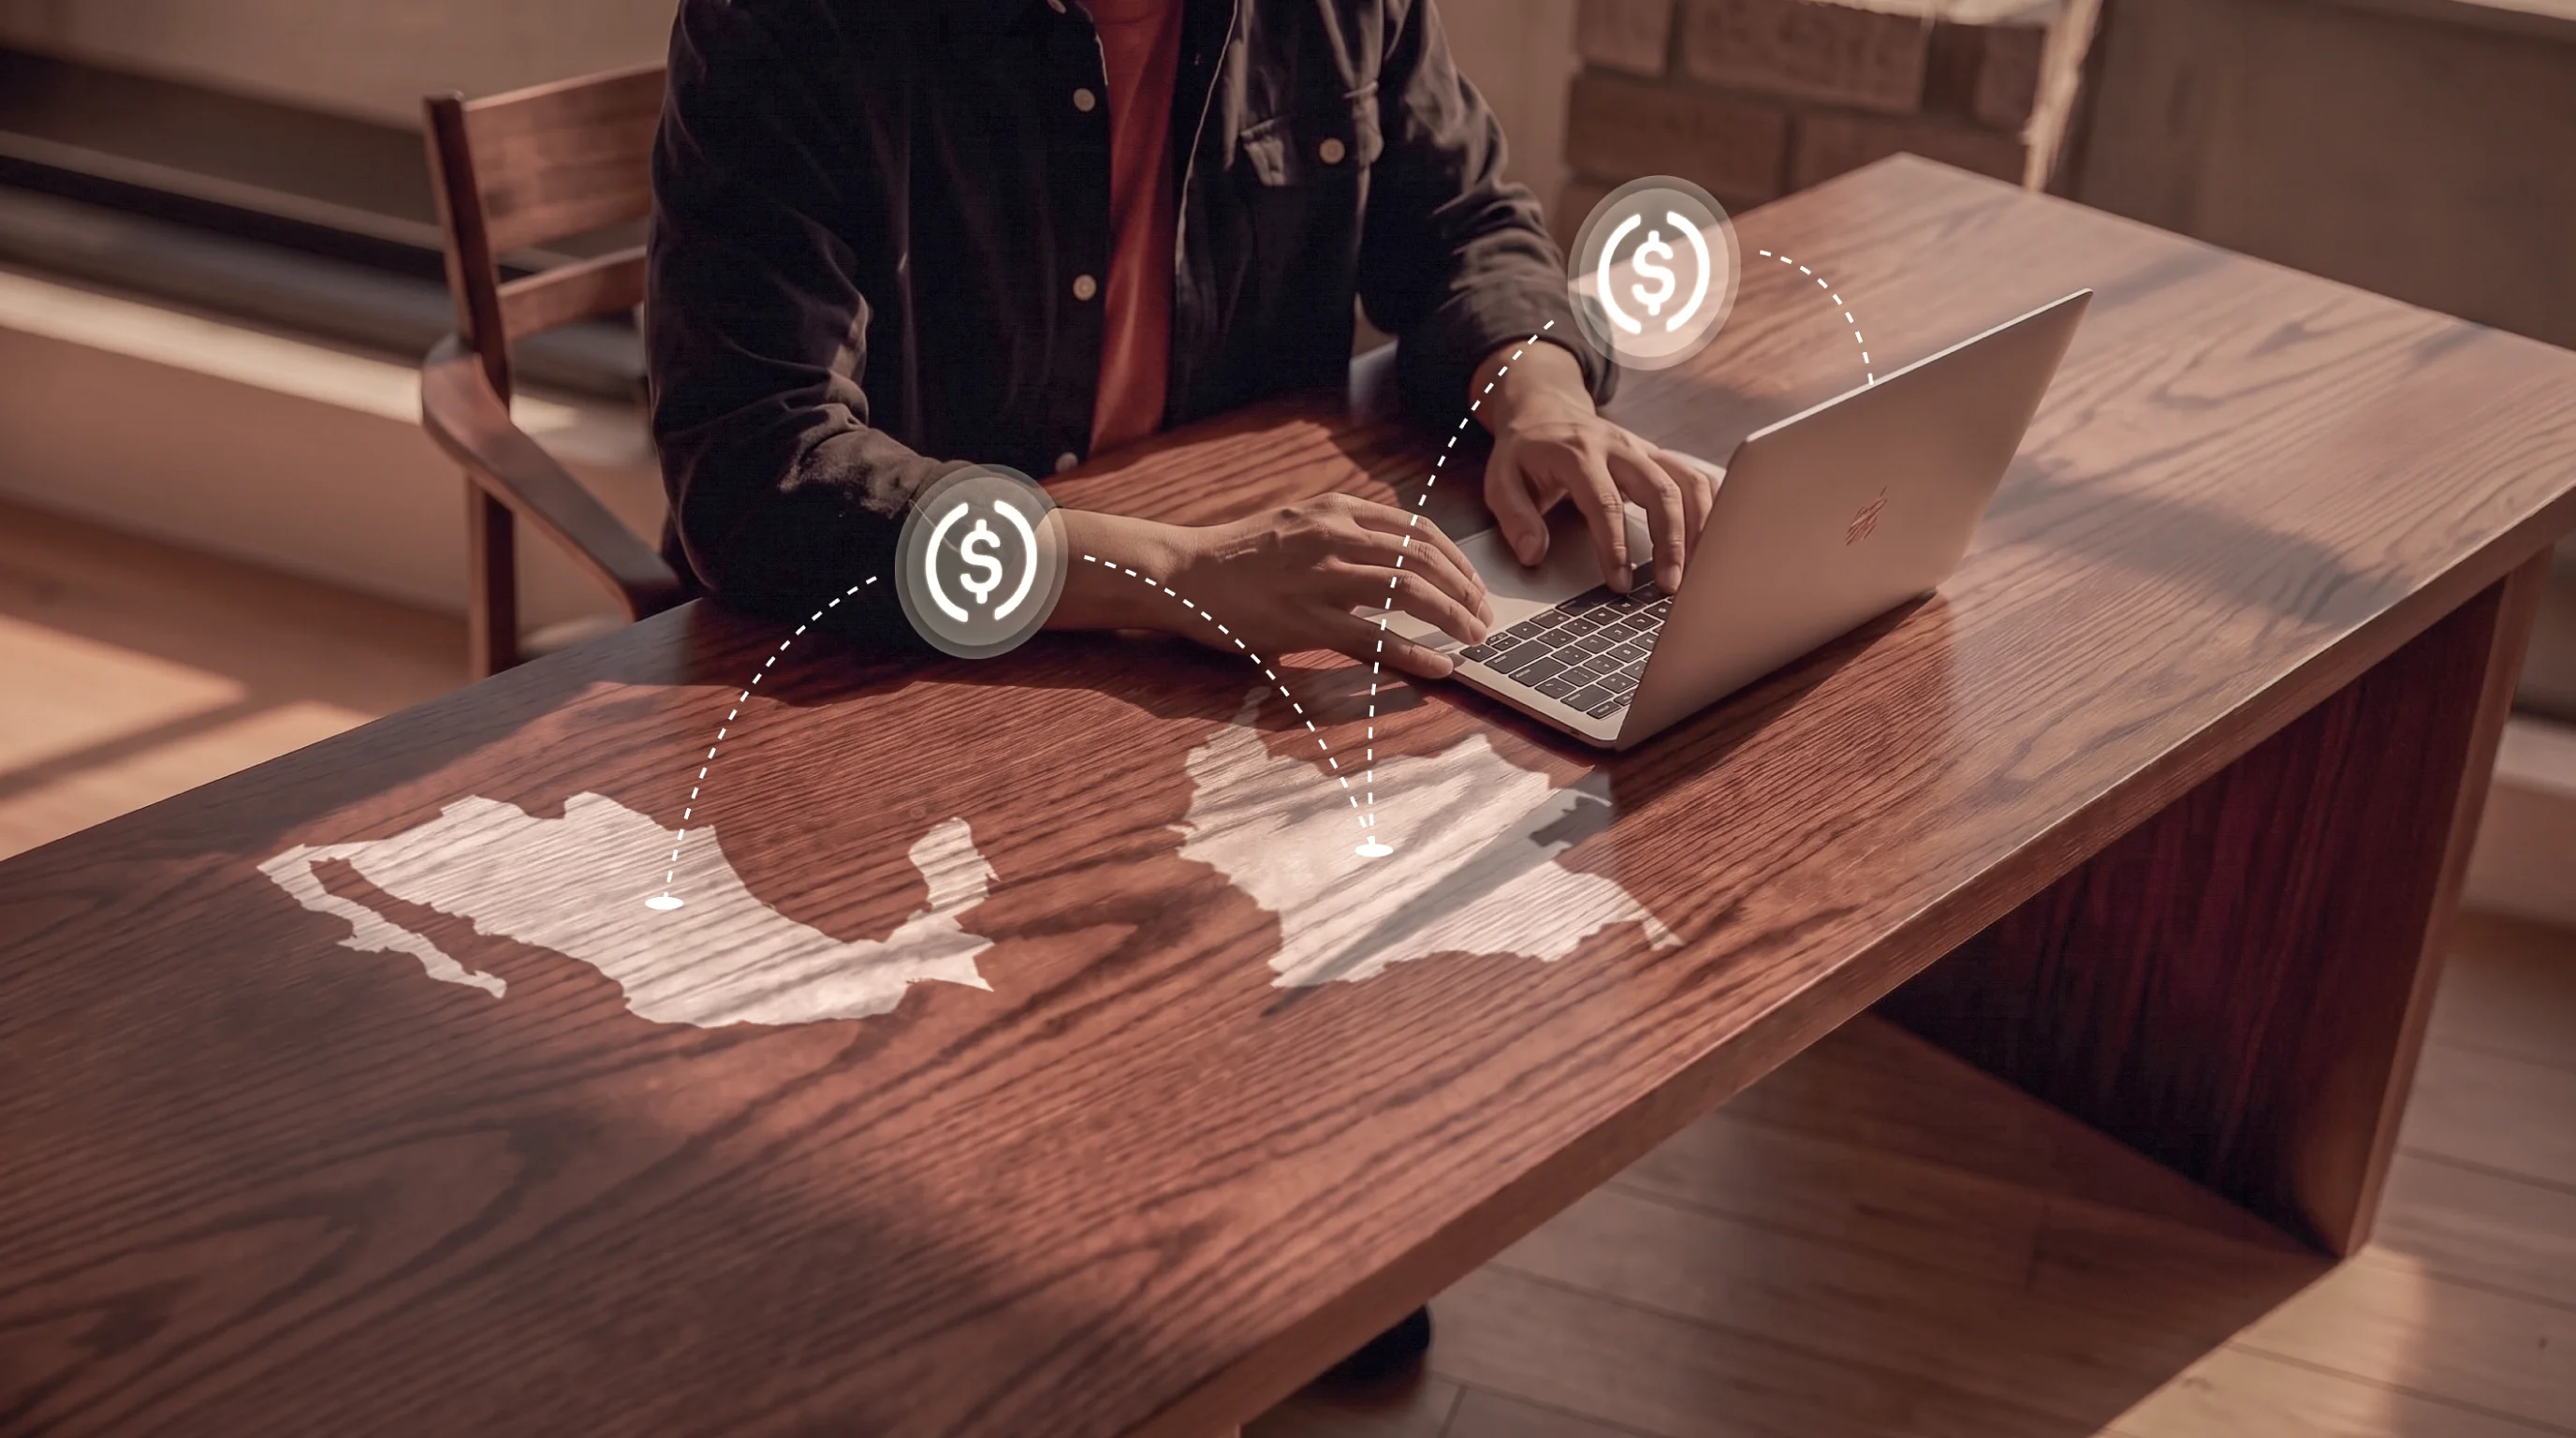
A tokenized dollar can cross a chain in seconds and then wait two days for a bank in Bogotá to open. That gap is the whole problem. For a business that has to pay salaries, suppliers, or taxes, stablecoin payments create value when the final leg lands in local currency, in a local account, or on a local rail without stalling. If a payment stalls at the fiat exit, it is not a settled payment, and you should consider it a pending problem.

On the other hand, an off-ramp alone doesn't settle a stablecoin payment. Settlement happens when local currency reaches the beneficiary's bank account through a local rail. Cobre's stablecoin payment infrastructure connects the off-ramp to local payouts over SPEI in Mexico and Bre-B or Fast Pay in Colombia, operating within the same API and dashboard.

Everything upstream—wallets, chains, and treasury policy—depends on that exit working. Cobre's stablecoin on-ramp and off-ramp documentation covers the mechanics of how both legs connect inside one platform.

The last-mile problem: why stablecoin speed doesn't matter if it can't land in local currency

The harder question it's how the dollars become pesos in a supplier's account, at a predictable rate, on a predictable day.

That final connection is where most stablecoin settlement designs break down. Blockchain payment rails clear continuously, but the local banking system they hand off to does not. If the exit depends on a correspondent bank, a weekend cutoff, or a manual instruction to a liquidity partner, the transfer inherits every delay the chain was supposed to remove.

Cross-border payments are judged by the beneficiary, not by the block explorer. A confirmed transaction hash is not a settled payment. Settlement happens when the counterparty's bank shows the funds, and your ledger can prove which on-chain movement produced them. 

Why "multi-rail" usually stops at US rails—and why that's not enough for LatAm

What global fiat and stablecoin infrastructure providers do cover

Most platforms that advertise stablecoins as a "first-class rail" pair them with ACH, RTP, FedNow, and wires. That's genuine multi-rail engineering, and it solves a real problem for companies paying inside the United States. (More on how these networks work in what are payment rails.)

The gap: no Mexican or Colombian instant rail is on that list

An off-ramp that ends in a US bank account leaves you with the question you started with: how do those dollars reach a vendor in Mexico City or a contractor in Medellin? The usual answer is another intermediary, another contract, another reconciliation file, and FX priced by whoever controls the last hop.

In LatAm, the rails that matter are SPEI in Mexico and other real-time payment rails like Bre-B or Fast Pay in Colombia. That’s where local beneficiaries receive money, in local currency, with local reference data. 

The token leg of stablecoins for cross-border payments is standardized and global, and the fiat leg is national and regulated, with different account formats, tax identifiers, and clearing behavior. Coverage of US rails says nothing about competence there.

How Cobre's stablecoin-to-fiat connection closes that gap

One dashboard and API for stablecoin off-ramp, SPEI, Bre-B, Fast Pay and ACH

Cobre treats the token leg and the fiat leg as one payment, not two systems stitched together. Stablecoin payins are screened before crediting a Cobre Balance, with chain, token, and hash metadata attached. Each stablecoin payout goes from a USD Cobre Global Balance to verified wallets on Ethereum, Tron, Solana, Polygon, Base, or XRPL, with automatic chain–token validation.

The same API also runs local payouts over SPEI in Mexico, and Bre-B, Fast Pay, ACH in Colombia, and Fedwire in the US. There's no separate off-ramp provider and no second integration.

Local settlement: converting straight into the rails your treasury already uses

The off-ramp doesn't land in a generic fiat account that then needs a second provider. It lands in a fiat Cobre Balance on the same platform your treasury already uses to pay locally. 

Conversion and payout are two steps inside one system, with one ledger and one set of reports.

Off-ramp in Colombia: from COPco to COP

COPco converts to COP in your Colombian Cobre Balance, with two settlement options. Standard settlement credits COP according to settlement windows at no cost. Instant settlement credits COP in real time.

Behind the scenes, the COPco is burned on-chain, and the COP credit is applied only once that operation is confirmed. If it fails, the debit is reversed automatically, and no conversion is applied.

Once the pesos are in your balance, they go out through the local payout rail that fits each payment.

Paying out with Bre-B: instant, key-based payments

Bre-B is Colombia's instant payment system. Payouts are sent to the recipient's Bre-B key instead of their full bank account details, and they settle in real time. Bre-B is the right rail for urgent payouts within its transaction limit. For larger amounts sent to a Bre-B key, Cobre resolves the key and routes the payment through Fast Pay automatically, so the treasury team doesn't have to pick a different rail.

Paying out with Fast Pay: account-based, any amount

Fast Pay sends COP directly to a recipient's savings, checking or electronic deposit account through Cobre's host-to-host connections with Colombia's main banks. Transfers arrive the same day or in near real time, without traditional ACH cycles, and with no amount limit. 

That makes Fast Pay a fit for large supplier payments or marketplace settlements funded by an off-ramp. If the recipient's bank isn't on Fast Pay, Cobre routes the payment through ACH automatically.

Off-ramp in Mexico: settling over SPEI

In Mexico, the local leg runs over SPEI, the Banco de México system that settles interbank transfers in real time, 24/7. Cobre is a direct SPEI participant, so MXN payouts don't depend on a reseller's connection. Once funds travelled through the stablecoin sandwich, from USD to USDT, they can be credited into your Cobre Balance in MXN, ready to be sent to any CLABE or SPEI-enabled card.

The stablecoin sandwich model uses the token purely as transport between two fiat positions, which limits exposure to market movement.

Unified reconciliation: on-chain and local-rail movements in one record

Every off-ramp produces a debit–credit pair tied to its originating money movement. Stablecoin payouts, conversions, and local payouts land in the same transaction list, balance statements, and CSV/JSON/PDF reports, including on-chain hash references where applicable.

Approval workflows (maker–checker), role-based permissions, and audit trails apply the same way whether money exits on-chain or through a local rail.

What to evaluate in a stablecoin-to-fiat payment provider

Before assuming "multi-rail" means real coverage in your corridor, ask:

  • Does the off-ramp connect directly to a local instant rail (SPEI, Bre-B), or only to generic ACH/wire? Cobre holds the connection itself to Mexican and Colombian rails.
  • Does reconciliation unify on-chain and local-rail movements in one report? Two exports means two reconciliations every month.
  • Can every payment (stablecoin, SPEI, Bre-B, ACH) be routed from the same platform without separate integrations? Each extra integration is another contract, another failure point, and another FX spread.
  • Are governance controls consistent across rails? Look for counterparty verification, maker–checker approvals, and audit trails that apply equally to on-chain and local payouts.

Where Cobre fits: Latam's multi-rail infrastructure for stablecoin and local payments

Cobre operates at the point where blockchain efficiency meets local currency liquidity: one integration for stablecoin transfers, real-time local payments in Mexico and Colombia, US dollar movement, 24/7 FX, and multi-bank reconciliation. Finance and engineering teams build once and pay everywhere in the region.

If your stablecoin strategy currently ends at a US bank account, schedule a demo to map the last mile into SPEI and Bre-B.

FAQ sobre infraestructura multi-riel de stablecoins

What is multi-rail infrastructure?

A single platform connected to several payment networks at once: blockchain networks plus local systems such as SPEI, Bre-B, PSE, and ACH, so one instruction can route through whichever rail delivers the funds.

How is an off-ramp different from multi-rail infrastructure?

An off-ramp converts tokens to fiat. Multi-rail infrastructure converts and then delivers, across countries, under one set of controls.

Is Cobre connected to SPEI and Bre-B?

Yes. Native integration with both enables real-time conversion from stablecoin to local currency and immediate dispersal to bank accounts.

Which rails besides stablecoins does Cobre support?

SPEI in Mexico; Bre-B, Cobre Fast Pay, and ACH in Colombia; Fedwire in the US; and cross-border payments with FX quotes.

Does the recipient need to understand digital assets?

No. They receive local currency in their bank account through their usual rail.

No items found.

Key takeaways

  • The off-ramp is the payment. A stablecoin transfer is settled when local currency reaches the beneficiary's bank, not when the chain confirms it.
  • US multi-rail stops at the border. Delivery inside Mexico and Colombia requires direct connectivity to SPEI, Bre-B, and Fast Pay.
  • One platform, one ledger. Off-ramp, local payouts, and reconciliation run from a single API and dashboard under the same controls.

A tokenized dollar can cross a chain in seconds and then wait two days for a bank in Bogotá to open. That gap is the whole problem. For a business that has to pay salaries, suppliers, or taxes, stablecoin payments create value when the final leg lands in local currency, in a local account, or on a local rail without stalling. If a payment stalls at the fiat exit, it is not a settled payment, and you should consider it a pending problem.

On the other hand, an off-ramp alone doesn't settle a stablecoin payment. Settlement happens when local currency reaches the beneficiary's bank account through a local rail. Cobre's stablecoin payment infrastructure connects the off-ramp to local payouts over SPEI in Mexico and Bre-B or Fast Pay in Colombia, operating within the same API and dashboard.

Everything upstream—wallets, chains, and treasury policy—depends on that exit working. Cobre's stablecoin on-ramp and off-ramp documentation covers the mechanics of how both legs connect inside one platform.

The last-mile problem: why stablecoin speed doesn't matter if it can't land in local currency

The harder question it's how the dollars become pesos in a supplier's account, at a predictable rate, on a predictable day.

That final connection is where most stablecoin settlement designs break down. Blockchain payment rails clear continuously, but the local banking system they hand off to does not. If the exit depends on a correspondent bank, a weekend cutoff, or a manual instruction to a liquidity partner, the transfer inherits every delay the chain was supposed to remove.

Cross-border payments are judged by the beneficiary, not by the block explorer. A confirmed transaction hash is not a settled payment. Settlement happens when the counterparty's bank shows the funds, and your ledger can prove which on-chain movement produced them. 

Why "multi-rail" usually stops at US rails—and why that's not enough for LatAm

What global fiat and stablecoin infrastructure providers do cover

Most platforms that advertise stablecoins as a "first-class rail" pair them with ACH, RTP, FedNow, and wires. That's genuine multi-rail engineering, and it solves a real problem for companies paying inside the United States. (More on how these networks work in what are payment rails.)

The gap: no Mexican or Colombian instant rail is on that list

An off-ramp that ends in a US bank account leaves you with the question you started with: how do those dollars reach a vendor in Mexico City or a contractor in Medellin? The usual answer is another intermediary, another contract, another reconciliation file, and FX priced by whoever controls the last hop.

In LatAm, the rails that matter are SPEI in Mexico and other real-time payment rails like Bre-B or Fast Pay in Colombia. That’s where local beneficiaries receive money, in local currency, with local reference data. 

The token leg of stablecoins for cross-border payments is standardized and global, and the fiat leg is national and regulated, with different account formats, tax identifiers, and clearing behavior. Coverage of US rails says nothing about competence there.

How Cobre's stablecoin-to-fiat connection closes that gap

One dashboard and API for stablecoin off-ramp, SPEI, Bre-B, Fast Pay and ACH

Cobre treats the token leg and the fiat leg as one payment, not two systems stitched together. Stablecoin payins are screened before crediting a Cobre Balance, with chain, token, and hash metadata attached. Each stablecoin payout goes from a USD Cobre Global Balance to verified wallets on Ethereum, Tron, Solana, Polygon, Base, or XRPL, with automatic chain–token validation.

The same API also runs local payouts over SPEI in Mexico, and Bre-B, Fast Pay, ACH in Colombia, and Fedwire in the US. There's no separate off-ramp provider and no second integration.

Local settlement: converting straight into the rails your treasury already uses

The off-ramp doesn't land in a generic fiat account that then needs a second provider. It lands in a fiat Cobre Balance on the same platform your treasury already uses to pay locally. 

Conversion and payout are two steps inside one system, with one ledger and one set of reports.

Off-ramp in Colombia: from COPco to COP

COPco converts to COP in your Colombian Cobre Balance, with two settlement options. Standard settlement credits COP according to settlement windows at no cost. Instant settlement credits COP in real time.

Behind the scenes, the COPco is burned on-chain, and the COP credit is applied only once that operation is confirmed. If it fails, the debit is reversed automatically, and no conversion is applied.

Once the pesos are in your balance, they go out through the local payout rail that fits each payment.

Paying out with Bre-B: instant, key-based payments

Bre-B is Colombia's instant payment system. Payouts are sent to the recipient's Bre-B key instead of their full bank account details, and they settle in real time. Bre-B is the right rail for urgent payouts within its transaction limit. For larger amounts sent to a Bre-B key, Cobre resolves the key and routes the payment through Fast Pay automatically, so the treasury team doesn't have to pick a different rail.

Paying out with Fast Pay: account-based, any amount

Fast Pay sends COP directly to a recipient's savings, checking or electronic deposit account through Cobre's host-to-host connections with Colombia's main banks. Transfers arrive the same day or in near real time, without traditional ACH cycles, and with no amount limit. 

That makes Fast Pay a fit for large supplier payments or marketplace settlements funded by an off-ramp. If the recipient's bank isn't on Fast Pay, Cobre routes the payment through ACH automatically.

Off-ramp in Mexico: settling over SPEI

In Mexico, the local leg runs over SPEI, the Banco de México system that settles interbank transfers in real time, 24/7. Cobre is a direct SPEI participant, so MXN payouts don't depend on a reseller's connection. Once funds travelled through the stablecoin sandwich, from USD to USDT, they can be credited into your Cobre Balance in MXN, ready to be sent to any CLABE or SPEI-enabled card.

The stablecoin sandwich model uses the token purely as transport between two fiat positions, which limits exposure to market movement.

Unified reconciliation: on-chain and local-rail movements in one record

Every off-ramp produces a debit–credit pair tied to its originating money movement. Stablecoin payouts, conversions, and local payouts land in the same transaction list, balance statements, and CSV/JSON/PDF reports, including on-chain hash references where applicable.

Approval workflows (maker–checker), role-based permissions, and audit trails apply the same way whether money exits on-chain or through a local rail.

What to evaluate in a stablecoin-to-fiat payment provider

Before assuming "multi-rail" means real coverage in your corridor, ask:

  • Does the off-ramp connect directly to a local instant rail (SPEI, Bre-B), or only to generic ACH/wire? Cobre holds the connection itself to Mexican and Colombian rails.
  • Does reconciliation unify on-chain and local-rail movements in one report? Two exports means two reconciliations every month.
  • Can every payment (stablecoin, SPEI, Bre-B, ACH) be routed from the same platform without separate integrations? Each extra integration is another contract, another failure point, and another FX spread.
  • Are governance controls consistent across rails? Look for counterparty verification, maker–checker approvals, and audit trails that apply equally to on-chain and local payouts.

Where Cobre fits: Latam's multi-rail infrastructure for stablecoin and local payments

Cobre operates at the point where blockchain efficiency meets local currency liquidity: one integration for stablecoin transfers, real-time local payments in Mexico and Colombia, US dollar movement, 24/7 FX, and multi-bank reconciliation. Finance and engineering teams build once and pay everywhere in the region.

If your stablecoin strategy currently ends at a US bank account, schedule a demo to map the last mile into SPEI and Bre-B.

FAQ sobre infraestructura multi-riel de stablecoins

What is multi-rail infrastructure?

A single platform connected to several payment networks at once: blockchain networks plus local systems such as SPEI, Bre-B, PSE, and ACH, so one instruction can route through whichever rail delivers the funds.

How is an off-ramp different from multi-rail infrastructure?

An off-ramp converts tokens to fiat. Multi-rail infrastructure converts and then delivers, across countries, under one set of controls.

Is Cobre connected to SPEI and Bre-B?

Yes. Native integration with both enables real-time conversion from stablecoin to local currency and immediate dispersal to bank accounts.

Which rails besides stablecoins does Cobre support?

SPEI in Mexico; Bre-B, Cobre Fast Pay, and ACH in Colombia; Fedwire in the US; and cross-border payments with FX quotes.

Does the recipient need to understand digital assets?

No. They receive local currency in their bank account through their usual rail.
Bre-B: la realidad de recaudos y pagos inmediatos
WEBINAR GRATUITO
20 OCT · 8:30 A. M. CST
Descubre cómo Samsung Colombia ha integrado Bre-B como medio de pago en su e-commerce. Explora casos de uso reales para tu negocio junto con expertos de Cobre y Credibanco.
Quiero registrarme
Emilio Uribe
Chief of Product & Operations
September 21, 2026

In this article

Emilio Uribe
Chief of Product & Operations
September 21, 2026
FREE WEBINAR
Discover how your company can use Bre-B.
Sign up
No items found.
Stablecoin

Off-ramp: how Cobre solves the last mile for stablecoin payments

Emilio Uribe
September 21, 2026
4 min read
No items found.
share this article

Key takeaways

  • The off-ramp is the payment. A stablecoin transfer is settled when local currency reaches the beneficiary's bank, not when the chain confirms it.
  • US multi-rail stops at the border. Delivery inside Mexico and Colombia requires direct connectivity to SPEI, Bre-B, and Fast Pay.
  • One platform, one ledger. Off-ramp, local payouts, and reconciliation run from a single API and dashboard under the same controls.

A tokenized dollar can cross a chain in seconds and then wait two days for a bank in Bogotá to open. That gap is the whole problem. For a business that has to pay salaries, suppliers, or taxes, stablecoin payments create value when the final leg lands in local currency, in a local account, or on a local rail without stalling. If a payment stalls at the fiat exit, it is not a settled payment, and you should consider it a pending problem.

On the other hand, an off-ramp alone doesn't settle a stablecoin payment. Settlement happens when local currency reaches the beneficiary's bank account through a local rail. Cobre's stablecoin payment infrastructure connects the off-ramp to local payouts over SPEI in Mexico and Bre-B or Fast Pay in Colombia, operating within the same API and dashboard.

Everything upstream—wallets, chains, and treasury policy—depends on that exit working. Cobre's stablecoin on-ramp and off-ramp documentation covers the mechanics of how both legs connect inside one platform.

The last-mile problem: why stablecoin speed doesn't matter if it can't land in local currency

The harder question it's how the dollars become pesos in a supplier's account, at a predictable rate, on a predictable day.

That final connection is where most stablecoin settlement designs break down. Blockchain payment rails clear continuously, but the local banking system they hand off to does not. If the exit depends on a correspondent bank, a weekend cutoff, or a manual instruction to a liquidity partner, the transfer inherits every delay the chain was supposed to remove.

Cross-border payments are judged by the beneficiary, not by the block explorer. A confirmed transaction hash is not a settled payment. Settlement happens when the counterparty's bank shows the funds, and your ledger can prove which on-chain movement produced them. 

Why "multi-rail" usually stops at US rails—and why that's not enough for LatAm

What global fiat and stablecoin infrastructure providers do cover

Most platforms that advertise stablecoins as a "first-class rail" pair them with ACH, RTP, FedNow, and wires. That's genuine multi-rail engineering, and it solves a real problem for companies paying inside the United States. (More on how these networks work in what are payment rails.)

The gap: no Mexican or Colombian instant rail is on that list

An off-ramp that ends in a US bank account leaves you with the question you started with: how do those dollars reach a vendor in Mexico City or a contractor in Medellin? The usual answer is another intermediary, another contract, another reconciliation file, and FX priced by whoever controls the last hop.

In LatAm, the rails that matter are SPEI in Mexico and other real-time payment rails like Bre-B or Fast Pay in Colombia. That’s where local beneficiaries receive money, in local currency, with local reference data. 

The token leg of stablecoins for cross-border payments is standardized and global, and the fiat leg is national and regulated, with different account formats, tax identifiers, and clearing behavior. Coverage of US rails says nothing about competence there.

How Cobre's stablecoin-to-fiat connection closes that gap

One dashboard and API for stablecoin off-ramp, SPEI, Bre-B, Fast Pay and ACH

Cobre treats the token leg and the fiat leg as one payment, not two systems stitched together. Stablecoin payins are screened before crediting a Cobre Balance, with chain, token, and hash metadata attached. Each stablecoin payout goes from a USD Cobre Global Balance to verified wallets on Ethereum, Tron, Solana, Polygon, Base, or XRPL, with automatic chain–token validation.

The same API also runs local payouts over SPEI in Mexico, and Bre-B, Fast Pay, ACH in Colombia, and Fedwire in the US. There's no separate off-ramp provider and no second integration.

Local settlement: converting straight into the rails your treasury already uses

The off-ramp doesn't land in a generic fiat account that then needs a second provider. It lands in a fiat Cobre Balance on the same platform your treasury already uses to pay locally. 

Conversion and payout are two steps inside one system, with one ledger and one set of reports.

Off-ramp in Colombia: from COPco to COP

COPco converts to COP in your Colombian Cobre Balance, with two settlement options. Standard settlement credits COP according to settlement windows at no cost. Instant settlement credits COP in real time.

Behind the scenes, the COPco is burned on-chain, and the COP credit is applied only once that operation is confirmed. If it fails, the debit is reversed automatically, and no conversion is applied.

Once the pesos are in your balance, they go out through the local payout rail that fits each payment.

Paying out with Bre-B: instant, key-based payments

Bre-B is Colombia's instant payment system. Payouts are sent to the recipient's Bre-B key instead of their full bank account details, and they settle in real time. Bre-B is the right rail for urgent payouts within its transaction limit. For larger amounts sent to a Bre-B key, Cobre resolves the key and routes the payment through Fast Pay automatically, so the treasury team doesn't have to pick a different rail.

Paying out with Fast Pay: account-based, any amount

Fast Pay sends COP directly to a recipient's savings, checking or electronic deposit account through Cobre's host-to-host connections with Colombia's main banks. Transfers arrive the same day or in near real time, without traditional ACH cycles, and with no amount limit. 

That makes Fast Pay a fit for large supplier payments or marketplace settlements funded by an off-ramp. If the recipient's bank isn't on Fast Pay, Cobre routes the payment through ACH automatically.

Off-ramp in Mexico: settling over SPEI

In Mexico, the local leg runs over SPEI, the Banco de México system that settles interbank transfers in real time, 24/7. Cobre is a direct SPEI participant, so MXN payouts don't depend on a reseller's connection. Once funds travelled through the stablecoin sandwich, from USD to USDT, they can be credited into your Cobre Balance in MXN, ready to be sent to any CLABE or SPEI-enabled card.

The stablecoin sandwich model uses the token purely as transport between two fiat positions, which limits exposure to market movement.

Unified reconciliation: on-chain and local-rail movements in one record

Every off-ramp produces a debit–credit pair tied to its originating money movement. Stablecoin payouts, conversions, and local payouts land in the same transaction list, balance statements, and CSV/JSON/PDF reports, including on-chain hash references where applicable.

Approval workflows (maker–checker), role-based permissions, and audit trails apply the same way whether money exits on-chain or through a local rail.

What to evaluate in a stablecoin-to-fiat payment provider

Before assuming "multi-rail" means real coverage in your corridor, ask:

  • Does the off-ramp connect directly to a local instant rail (SPEI, Bre-B), or only to generic ACH/wire? Cobre holds the connection itself to Mexican and Colombian rails.
  • Does reconciliation unify on-chain and local-rail movements in one report? Two exports means two reconciliations every month.
  • Can every payment (stablecoin, SPEI, Bre-B, ACH) be routed from the same platform without separate integrations? Each extra integration is another contract, another failure point, and another FX spread.
  • Are governance controls consistent across rails? Look for counterparty verification, maker–checker approvals, and audit trails that apply equally to on-chain and local payouts.

Where Cobre fits: Latam's multi-rail infrastructure for stablecoin and local payments

Cobre operates at the point where blockchain efficiency meets local currency liquidity: one integration for stablecoin transfers, real-time local payments in Mexico and Colombia, US dollar movement, 24/7 FX, and multi-bank reconciliation. Finance and engineering teams build once and pay everywhere in the region.

If your stablecoin strategy currently ends at a US bank account, schedule a demo to map the last mile into SPEI and Bre-B.

FAQ sobre infraestructura multi-riel de stablecoins

What is multi-rail infrastructure?

A single platform connected to several payment networks at once: blockchain networks plus local systems such as SPEI, Bre-B, PSE, and ACH, so one instruction can route through whichever rail delivers the funds.

How is an off-ramp different from multi-rail infrastructure?

An off-ramp converts tokens to fiat. Multi-rail infrastructure converts and then delivers, across countries, under one set of controls.

Is Cobre connected to SPEI and Bre-B?

Yes. Native integration with both enables real-time conversion from stablecoin to local currency and immediate dispersal to bank accounts.

Which rails besides stablecoins does Cobre support?

SPEI in Mexico; Bre-B, Cobre Fast Pay, and ACH in Colombia; Fedwire in the US; and cross-border payments with FX quotes.

Does the recipient need to understand digital assets?

No. They receive local currency in their bank account through their usual rail.

Written by:
Emilio Uribe
Chief of Product & Operations

Let's talk about how to optimize your payments

Fill out the form and we will contact you within 24 business hours
+3x
faster payment processing.
-56%
in transactional errors with Cobre APIs.
-50h
per month spent on reconciliation, now automated.
+3x
faster payment processing.
-56%
-56%
-50h
per month spent on reconciliation, now automated.
Optimize your financial processes with Cobre
Centralize your local and international operations on a single platform.
Contact Sales
/Webinar/ //Webinar