
A fiat-backed stablecoin is a stable cryptocurrency backed by fiat currency. Within the crypto ecosystem, there is a type of non-volatile crypto asset that is attractive to traditional banks: the stablecoin.
A stablecoin maintains its value thanks to a 1:1 backing. This backing can take four forms: fiat-backed, commodity-backed, backed by smart contracts, or backed by other crypto assets.
You can read more about what a stablecoin is, the types of backing, and its uses in our article.
Among the various types of backing, the fiat-backed stablecoin builds trust through its parity mechanism: for every stablecoin issued, there is an equivalent amount in fiat currency, which can be euros, dollars, Mexican pesos, or Colombian pesos.
Additionally, there are regulations governing the transparency of reserves for fiat-backed stablecoins.
Some of the best-known stablecoins are USDC, USDT (Tether), and EURR.
These stablecoins are backed by fiat currency, which means they maintain a 1:1 peg with a fiat currency.
Historically, these tools were the exclusive domain of fintech companies. However, the narrative shifted between 2024 and 2025.
Today, traditional banks, in addition to custodying these crypto assets, have begun to roll out their own infrastructure for cross-border payments using fiat-backed stablecoins at an institutional scale.
These are some of the best-known fiat-backed stablecoins:
For chief financial officers (CFOs), the appeal of a fiat-backed stablecoin lies in its operational efficiency.
The ability to settle international transactions in minutes, 24/7, and at reduced costs has made stablecoins a critical infrastructure.
Critical infrastructure refers to systems, facilities, and assets that are vital to the functioning of the economy and society.
Furthermore, critical infrastructure consists of physical and virtual components that are interconnected and interdependent.
In the financial world, critical infrastructure can include banks, stock exchanges, and payment systems. In the fintech world, a stablecoin payment system qualifies as critical infrastructure.
Another factor influencing critical infrastructure is that governments implement rules and regulations governing how it should be managed.
Entities such as the United States and the European Union have regulations governing the use and issuance of stablecoins.
The banking sector’s new stance on stablecoins is driven by three factors: competitive pressure from fintechs, regulatory clarity (such as the MiCA law in Europe or the GENIUS Act in the U.S.), and the maturity of institutional custody.
Regulatory clarity has allowed banks to begin using stablecoins, separating crypto volatility from the efficiency of stablecoins.
Today, stablecoins are managed as financial infrastructure, not as risky assets.
Other key factors that drove traditional banks to integrate stablecoins into their operations included the following:
Fireblocks’ “State of Stablecoins 2025” report found that 90% of global financial institutions either use stablecoins or are in the process of incorporating them into their operations.
45% of transactions made with stablecoins are for cross-border payments, trade settlement, or corporate treasury.
Institutions such as Visa and Mastercard are also taking steps in this direction. For example, the Mastercard stablecoin was announced as part of a multilateral integration.
Through its platform, Mastercard supports stablecoins such as USDG (with Paxos), FIUSD (with Fiserv), PYUSD (with PayPal), and USDC (with Circle), thereby enabling transactions for both consumers and merchants.
Financial institutions that have not yet formally adopted it are either in the pilot phase or in the strategic planning stage for implementation.
The JP Morgan stablecoin (JPM Coin) is the stablecoin that global financial institution JP Morgan designed as a financial solution for institutions, combined with a deposit token.
JP Morgan, which processes over $1 trillion in payments daily, decided to integrate a stablecoin into its operations to enable real-time transactions (24/7) without time restrictions, as well as B2B payments and transfers via blockchain.
A G7 stablecoin is set to become a reality by the second half of 2026. In October 2025, a consortium of ten financial giants—including Santander, Bank of America, Barclays, Citi, and Goldman Sachs—announced the creation of a multi-currency stablecoin pegged to G7 currencies.
This project is a milestone: it uses public blockchains (such as Ethereum) but under strict regulatory compliance.
The goal is for companies to make international payments without needing to “understand” blockchain, eliminating the friction of the traditional SWIFT system.
The ten banks that announced this multi-currency stablecoin collectively manage over $50 trillion in assets. Their entry into the stablecoin market represents the most significant institutional move into digital assets.
The official statement outlines the following operational guidelines:
In June 2025, Société Générale issued its USD CoinVertible (USDCV) through its subsidiary SG-FORGE. Its stablecoin is backed by dollars on the Ethereum and Solana public blockchains.
Société Générale, which has €1.5 trillion in assets under management and operates in 61 countries, made history as the first regulated global bank to issue a dollar-backed stablecoin on public blockchains.
One of the most significant differences between a stablecoin issued by a private company and one issued by a bank is strict regulation and liquidity.
The USDCV, for example, is issued by a digital subsidiary of a European G-SIB bank: it is subject to the same regulatory requirements as any commercial bank deposit.
Since 2023, Japan has been leading the way with Project PAX, a stablecoin platform for cross-border transactions designed for commercial settlement.
On September 5, 2024, Japan’s largest banks (Mitsubishi UFJ Bank, Sumitomo Mitsui Banking Corporation, and Mizuho Bank) launched a stablecoin project backed by domestic deposits (trust bank), enabling fund transfers and trust companies.
Project PAX is a stablecoin initiative for cross-border transactions:
According to Mitsubishi UFJ Bank: “Deposits in the trust bank are bankruptcy-remote, making it potentially the most secure stablecoin for use on public blockchains.”
Latin America is not far behind. BTG Pactual, Latin America’s largest investment bank, issued its first dollar-backed stablecoin in April 2023 on its crypto platform, Mynth.
The BTG Dol stablecoin is backed by the U.S. dollar. BTG Pactual designed this stablecoin as an opportunity to dollarize its shares safely, efficiently, and simply.
Brazil is another country moving steadily toward the use of stablecoins for transactions. In November 2025, Brazil announced its entry into the stablecoin market.
Recently, in January of this year, BRL1 Network announced the list of exchanges for its BRL1 stablecoin.
A bank-backed stablecoin offers a higher level of transparency than a traditional bank balance sheet. While a typical bank operates on a fractional reserve system, institutional stablecoins are usually 100% backed by cash or high-quality liquid assets (such as short-term Treasury bills).
The true revolution of stablecoins lies in the infrastructure. When a bank uses a fiat-backed stablecoin on a public blockchain, it enables interoperability.
Currently, there is $272.94 billion worth of stablecoins in circulation, according to Visa On Chain Analytics metrics.
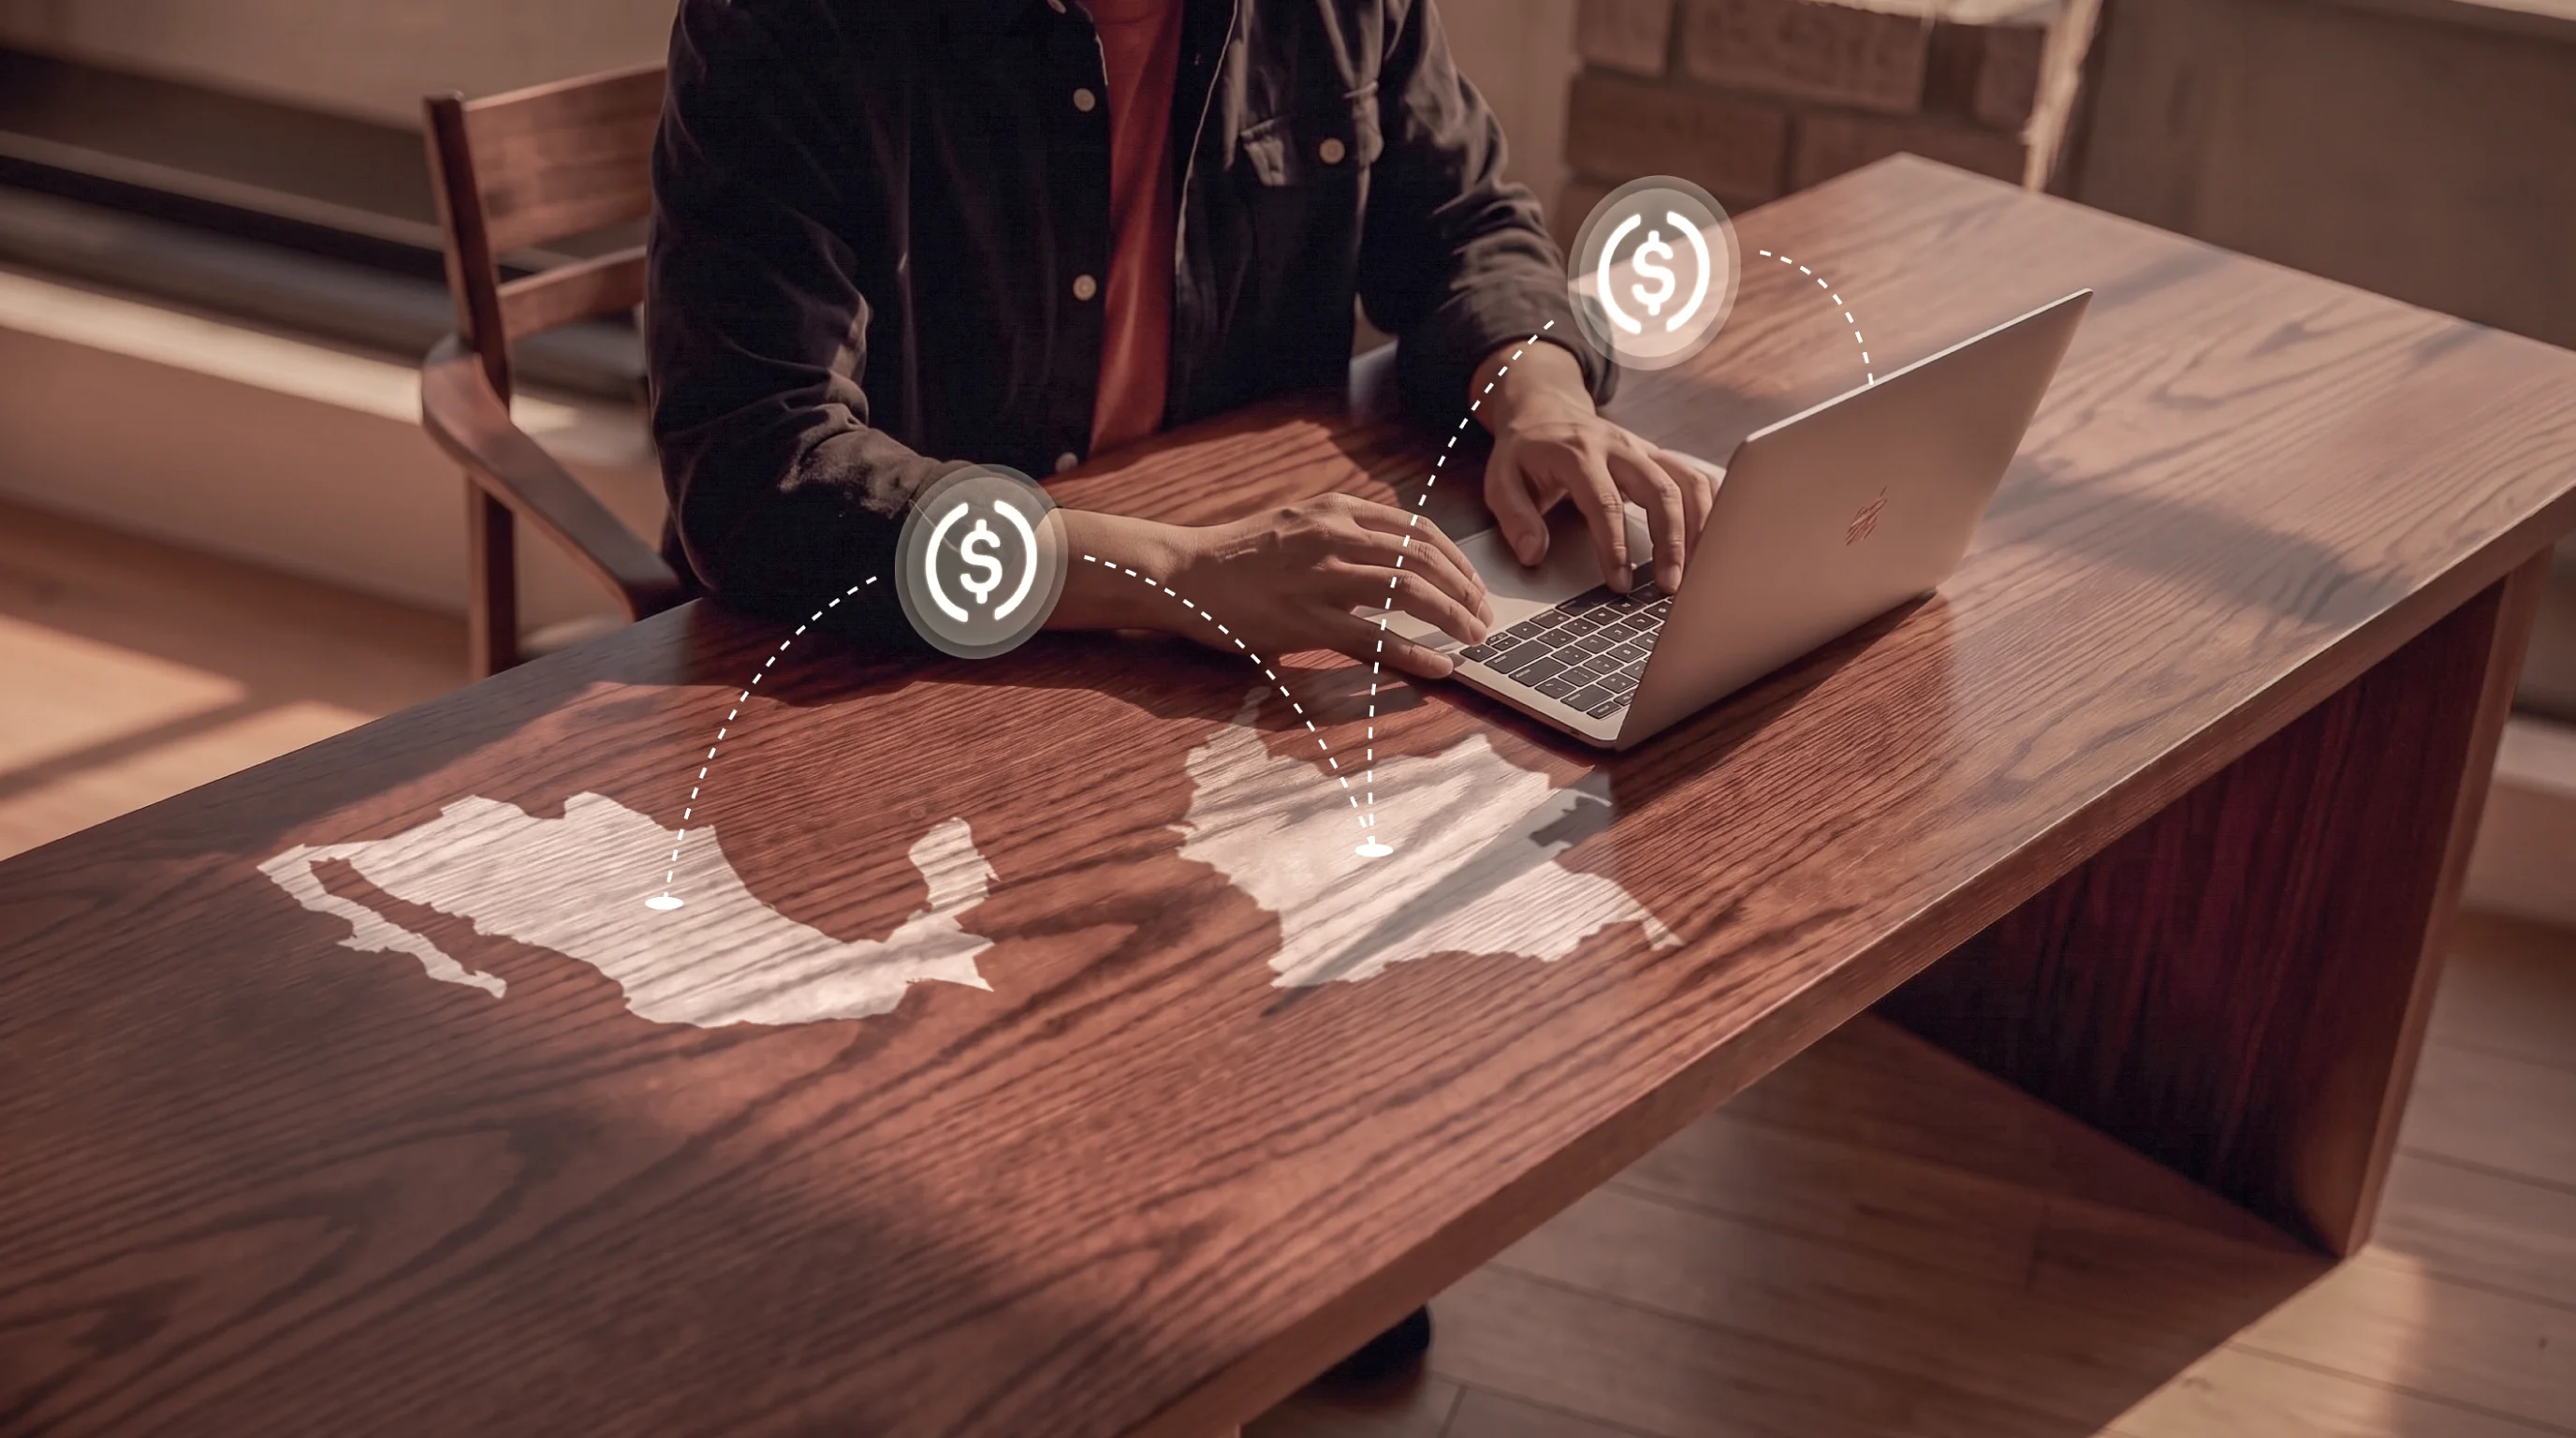
This means that a company in Colombia or Mexico can receive a payment on a Saturday at 11:00 p.m. and convert it to local currency immediately.
The blockchain has no "business hours." By eliminating intermediary correspondent banks, not only are processing times reduced, but so are the opaque international transfer fees that often impact companies’ cash flow.
The landscape of cross-border transactions and international payments using stablecoins has proven its efficiency.
The entry of institutions such as JPMorgan, Société Générale, and the G7 consortium confirms that fiat-backed stablecoins are no longer just a fintech alternative, but a new infrastructure for global banking.
For companies with cross-border operations, this represents three immediate competitive advantages:
The transition of stablecoins as a tool for corporate treasury is now a reality. Today, companies have the opportunity to modernize their payment infrastructure, operating with the speed of blockchain and the reliability of traditional banking.
On-ramps and off-ramps are the "digital bridges" that connect the traditional financial system to blockchain networks.
A "stablecoin sandwich" is a cross-border payment architecture designed to give businesses the speed of crypto without forcing them to hold or manage digital assets. It works in three distinct steps:
Disclaimer
This document is for informational and educational purposes only. It does not constitute legal, financial, tax, or investment advice. Decisions regarding the adoption of stablecoins must be evaluated within the specific context of each company, including risk exposure, applicable regulatory frameworks, and guidance from independent legal counsel.
A fiat-backed stablecoin is a stable cryptocurrency backed by fiat currency. Within the crypto ecosystem, there is a type of non-volatile crypto asset that is attractive to traditional banks: the stablecoin.
A stablecoin maintains its value thanks to a 1:1 backing. This backing can take four forms: fiat-backed, commodity-backed, backed by smart contracts, or backed by other crypto assets.
You can read more about what a stablecoin is, the types of backing, and its uses in our article.
Among the various types of backing, the fiat-backed stablecoin builds trust through its parity mechanism: for every stablecoin issued, there is an equivalent amount in fiat currency, which can be euros, dollars, Mexican pesos, or Colombian pesos.
Additionally, there are regulations governing the transparency of reserves for fiat-backed stablecoins.
Some of the best-known stablecoins are USDC, USDT (Tether), and EURR.
These stablecoins are backed by fiat currency, which means they maintain a 1:1 peg with a fiat currency.
Historically, these tools were the exclusive domain of fintech companies. However, the narrative shifted between 2024 and 2025.
Today, traditional banks, in addition to custodying these crypto assets, have begun to roll out their own infrastructure for cross-border payments using fiat-backed stablecoins at an institutional scale.
These are some of the best-known fiat-backed stablecoins:
For chief financial officers (CFOs), the appeal of a fiat-backed stablecoin lies in its operational efficiency.
The ability to settle international transactions in minutes, 24/7, and at reduced costs has made stablecoins a critical infrastructure.
Critical infrastructure refers to systems, facilities, and assets that are vital to the functioning of the economy and society.
Furthermore, critical infrastructure consists of physical and virtual components that are interconnected and interdependent.
In the financial world, critical infrastructure can include banks, stock exchanges, and payment systems. In the fintech world, a stablecoin payment system qualifies as critical infrastructure.
Another factor influencing critical infrastructure is that governments implement rules and regulations governing how it should be managed.
Entities such as the United States and the European Union have regulations governing the use and issuance of stablecoins.
The banking sector’s new stance on stablecoins is driven by three factors: competitive pressure from fintechs, regulatory clarity (such as the MiCA law in Europe or the GENIUS Act in the U.S.), and the maturity of institutional custody.
Regulatory clarity has allowed banks to begin using stablecoins, separating crypto volatility from the efficiency of stablecoins.
Today, stablecoins are managed as financial infrastructure, not as risky assets.
Other key factors that drove traditional banks to integrate stablecoins into their operations included the following:
Fireblocks’ “State of Stablecoins 2025” report found that 90% of global financial institutions either use stablecoins or are in the process of incorporating them into their operations.
45% of transactions made with stablecoins are for cross-border payments, trade settlement, or corporate treasury.
Institutions such as Visa and Mastercard are also taking steps in this direction. For example, the Mastercard stablecoin was announced as part of a multilateral integration.
Through its platform, Mastercard supports stablecoins such as USDG (with Paxos), FIUSD (with Fiserv), PYUSD (with PayPal), and USDC (with Circle), thereby enabling transactions for both consumers and merchants.
Financial institutions that have not yet formally adopted it are either in the pilot phase or in the strategic planning stage for implementation.
The JP Morgan stablecoin (JPM Coin) is the stablecoin that global financial institution JP Morgan designed as a financial solution for institutions, combined with a deposit token.
JP Morgan, which processes over $1 trillion in payments daily, decided to integrate a stablecoin into its operations to enable real-time transactions (24/7) without time restrictions, as well as B2B payments and transfers via blockchain.
A G7 stablecoin is set to become a reality by the second half of 2026. In October 2025, a consortium of ten financial giants—including Santander, Bank of America, Barclays, Citi, and Goldman Sachs—announced the creation of a multi-currency stablecoin pegged to G7 currencies.
This project is a milestone: it uses public blockchains (such as Ethereum) but under strict regulatory compliance.
The goal is for companies to make international payments without needing to “understand” blockchain, eliminating the friction of the traditional SWIFT system.
The ten banks that announced this multi-currency stablecoin collectively manage over $50 trillion in assets. Their entry into the stablecoin market represents the most significant institutional move into digital assets.
The official statement outlines the following operational guidelines:
In June 2025, Société Générale issued its USD CoinVertible (USDCV) through its subsidiary SG-FORGE. Its stablecoin is backed by dollars on the Ethereum and Solana public blockchains.
Société Générale, which has €1.5 trillion in assets under management and operates in 61 countries, made history as the first regulated global bank to issue a dollar-backed stablecoin on public blockchains.
One of the most significant differences between a stablecoin issued by a private company and one issued by a bank is strict regulation and liquidity.
The USDCV, for example, is issued by a digital subsidiary of a European G-SIB bank: it is subject to the same regulatory requirements as any commercial bank deposit.
Since 2023, Japan has been leading the way with Project PAX, a stablecoin platform for cross-border transactions designed for commercial settlement.
On September 5, 2024, Japan’s largest banks (Mitsubishi UFJ Bank, Sumitomo Mitsui Banking Corporation, and Mizuho Bank) launched a stablecoin project backed by domestic deposits (trust bank), enabling fund transfers and trust companies.
Project PAX is a stablecoin initiative for cross-border transactions:
According to Mitsubishi UFJ Bank: “Deposits in the trust bank are bankruptcy-remote, making it potentially the most secure stablecoin for use on public blockchains.”
Latin America is not far behind. BTG Pactual, Latin America’s largest investment bank, issued its first dollar-backed stablecoin in April 2023 on its crypto platform, Mynth.
The BTG Dol stablecoin is backed by the U.S. dollar. BTG Pactual designed this stablecoin as an opportunity to dollarize its shares safely, efficiently, and simply.
Brazil is another country moving steadily toward the use of stablecoins for transactions. In November 2025, Brazil announced its entry into the stablecoin market.
Recently, in January of this year, BRL1 Network announced the list of exchanges for its BRL1 stablecoin.
A bank-backed stablecoin offers a higher level of transparency than a traditional bank balance sheet. While a typical bank operates on a fractional reserve system, institutional stablecoins are usually 100% backed by cash or high-quality liquid assets (such as short-term Treasury bills).
The true revolution of stablecoins lies in the infrastructure. When a bank uses a fiat-backed stablecoin on a public blockchain, it enables interoperability.
Currently, there is $272.94 billion worth of stablecoins in circulation, according to Visa On Chain Analytics metrics.
This means that a company in Colombia or Mexico can receive a payment on a Saturday at 11:00 p.m. and convert it to local currency immediately.
The blockchain has no "business hours." By eliminating intermediary correspondent banks, not only are processing times reduced, but so are the opaque international transfer fees that often impact companies’ cash flow.
The landscape of cross-border transactions and international payments using stablecoins has proven its efficiency.
The entry of institutions such as JPMorgan, Société Générale, and the G7 consortium confirms that fiat-backed stablecoins are no longer just a fintech alternative, but a new infrastructure for global banking.
For companies with cross-border operations, this represents three immediate competitive advantages:
The transition of stablecoins as a tool for corporate treasury is now a reality. Today, companies have the opportunity to modernize their payment infrastructure, operating with the speed of blockchain and the reliability of traditional banking.
On-ramps and off-ramps are the "digital bridges" that connect the traditional financial system to blockchain networks.
A "stablecoin sandwich" is a cross-border payment architecture designed to give businesses the speed of crypto without forcing them to hold or manage digital assets. It works in three distinct steps:
Disclaimer
This document is for informational and educational purposes only. It does not constitute legal, financial, tax, or investment advice. Decisions regarding the adoption of stablecoins must be evaluated within the specific context of each company, including risk exposure, applicable regulatory frameworks, and guidance from independent legal counsel.