International trade in Latin America has grown steadily over the past decade, with countries like Mexico and Colombia positioning themselves as major trade hubs in the region.
However, companies operating cross-border still face significant challenges in their foreign currency transactions: from exchange rate volatility to manual processes that consume valuable hours of financial teams’ time.
Every foreign currency transaction—whether to pay an international supplier or receive export proceeds—involves navigating a complex foreign exchange market with costs that aren’t always transparent.
For many companies, this translates to squeezed margins, tied-up working capital, and exposure to foreign exchange risks that are difficult to mitigate.
This guide explores what foreign currency transactions are, why your company needs them, the main operational challenges you’re likely facing, and how modern payment infrastructure is changing the game for Latin American companies.
Foreign exchange trading refers to transactions in which companies buy, sell, or exchange currencies to conduct international business activities.
We are not talking about speculative trading in the foreign exchange market, but rather about real operational needs: paying a supplier in China, receiving payment for an export in dollars, or transferring funds between subsidiaries in different countries.
Foreign currency transactions directly impact three critical areas of a business:
Foreign trade is the primary driver of foreign exchange transactions.
If you are an importer, every payment order to your international suppliers requires converting your local currency into the corresponding foreign currency. These foreign exchange costs must be carefully managed to maintain your profit margins.
Imagine you import electronic components from Asia: you have to conduct FX transactions to pay in dollars or yuan, and assume the risk of exchange rate fluctuations between the time you quote and when you finally pay.
The impact of foreign currency transactions on your cost structure can be significant if the currency market moves unfavorably during this period.
Exporters face the opposite challenge.
You receive revenue in foreign currency that you need to convert to local currency to cover operating costs, pay payroll, and report results.
The decision of when to make that conversion, considering the subsequent exchange rate valuation, can generate foreign exchange gains or losses that make a significant difference in your margins.
If your company operates in multiple countries, FX transactions are a daily necessity for efficient cash management:
Another alternative for corporate treasury is the use of stablecoins for cross-border transactions or B2B payments. Learn what a stablecoin is, its types, and regulations.
The volatility of average exchange rates poses a real risk to companies with foreign currency exposure.
The Colombian peso can fluctuate between 8% and 12% annually, and the Mexican peso exhibits similar patterns of volatility. This volatility can literally wipe out your operating margins if not managed properly, especially when considering the effects of inflation on purchasing power.
Hedging strategies allow you to lock in future rates in the foreign exchange market, protecting your budgets against exchange rate fluctuations and giving you the financial predictability you need to make strategic decisions with confidence.
However, not all volatility requires long-term hedging instruments. There is a different, more immediate but equally costly exposure: the one that occurs in the hours or days between the moment you decide to make a payment and when you can actually complete it.
This is where locking in the exchange rate at the time of the decision becomes critical.
Unlike traditional hedging instruments that lock in rates for distant future dates, this approach protects trades you’ve already decided to execute but that face inevitable operational delays: internal approvals, settlement cycles, and transaction aggregation.
You are not speculating on future market movements or committing capital long-term; you are simply eliminating the uncertainty of that small but costly time gap between decision and execution. It is tactical hedging for immediate transactions, not a strategy for future exposures, and it becomes a natural complement to your broader foreign exchange risk management tools.
Although currency volatility is a known risk, many mid-sized companies face a more immediate problem: they cannot access the instruments that would allow them to protect themselves.
Financial corporations and traditional banks set requirements that work well for large corporations but prove prohibitive for smaller-scale companies.
The result is a significant gap: companies that fully understand foreign exchange risk and want to protect themselves, but simply do not qualify for the available tools.
Unfortunately, they find themselves in a middle ground where they are too large to ignore the risk, but too small to access traditional foreign exchange market solutions.
One of the most common challenges in foreign exchange transactions is determining the actual cost of your transactions.
The exchange rates you receive do not always reflect the actual rates you will end up paying, which directly affects the valuation of your transactions.
Bank spreads are not visible upfront, and when money passes through domestic intermediaries or correspondent banks, fees accumulate in ways you didn’t anticipate.
Together, these costs can represent between 2% and 5% of the total transaction amount, depending on the route, the currencies involved, and the participating banks.
Traditional international transfers via SWIFT can take between 3 and 5 business days to complete.
This delay has direct implications for your working capital: funds that are "in transit" are not generating value or available for other operations, and foreign currency deposits remain tied up during that period.
Furthermore, when you identify a favorable exchange rate today but your conversion and transfer process takes several days, you will likely miss that window of opportunity.
The closing exchange rate may vary significantly from when you initiated the transaction.
This is precisely the most frustrating liquidity problem: to avoid missing a favorable rate, many companies are forced to bring forward the conversion and keep capital locked up in the target currency until they actually need to make the payment.
But that means tying up funds that could be financing other operations or capitalizing on other opportunities. The alternative is to be able to lock in that favorable rate the moment you identify it, without having to move or reserve a rate until you’re actually ready to execute.
This transforms liquidity management: you no longer have to choose between protecting your rate or maintaining flexibility with your capital.
The typical process for a manual international transfer takes between 20 and 30 minutes: preparing the information in Excel, logging into multiple banking portals, copying data field by field, uploading supporting documentation, requesting approval tokens.
This manual process increases the risk of error in each of your foreign currency transactions.
When these errors occur, the costs of correction include bank investigation fees and additional delays of several days, not to mention the time your team spends resolving the issue.
Each country has its own requirements for foreign exchange transactions.
Navigating these multiple, changing, and sometimes conflicting requirements across jurisdictions represents a significant operational burden, especially for companies without dedicated compliance departments.
Furthermore, the accounting treatment of these transactions under financial reporting standards such as International Financial Reporting Standards (IFRS) adds another layer of complexity, particularly in calculating fair value and the resulting differences between various measurement methods.
Latin American companies have three main options for managing their foreign exchange transactions, each with specific advantages and limitations:
The most common option due to trust and existing banking relationships. Banks act as intermediaries in the foreign exchange market, facilitating access to the currency market. However, they have significant operational limitations:
They offer more competitive spreads for spot transactions and more streamlined processes than banks. Their limitations include:
The latest option on the market, offering clear technological advantages: APIs for integration, cost transparency, and digitized processes. The experience varies by provider in terms of currency coverage, compliance robustness, and quality of support.
The most advanced platforms, such as Cobre’s Cross Border Payments, operate with an architecture that connects multiple global financial infrastructure providers, offering coverage in over 70 countries and 40 currencies.
What sets these modern platforms apart is the combination of operational flexibility—you can use APIs for full automation of international payments or web interfaces for manual operations—with built-in compliance that automatically handles KYC and AML in accordance with each jurisdiction’s regulations.
The result is that you no longer need to establish banking relationships in every country where you operate; you access the global infrastructure through a single integration.
There is a significant gap for mid-sized companies. They are too large for currency exchange firms to handle their volume and operational complexity, yet too small to qualify for the best terms and services offered by corporate banks.
This gap is precisely where modern fintech infrastructure is making the greatest impact.
Mid-sized companies can now access capabilities that were previously reserved only for large corporations: international payment APIs, accelerated settlement, real-time visibility, and unified management of multiple currencies and jurisdictions.
Platforms like Cobre are building infrastructure specifically tailored to the Latin American context, with operations in the region.
The way companies conduct foreign exchange transactions is evolving rapidly in Latin America.
What used to require calling your bank to get a rate quote, waiting for approvals, logging into multiple portals, and waiting days for the conversion and transfer can now be handled through technology platforms designed specifically for corporate FX transactions.
This transformation not only reduces costs: it fundamentally changes companies’ ability to capitalize on favorable timing in conversions, protect margins, and maintain optimal liquidity in their international operations.
Latin American companies conducting foreign currency transactions need an infrastructure that understands the region’s unique characteristics.
At Cobre, we’ve built exactly that: a platform designed for companies operating in and from Colombia and Mexico, integrating cross-border FX capabilities with local payment rails.
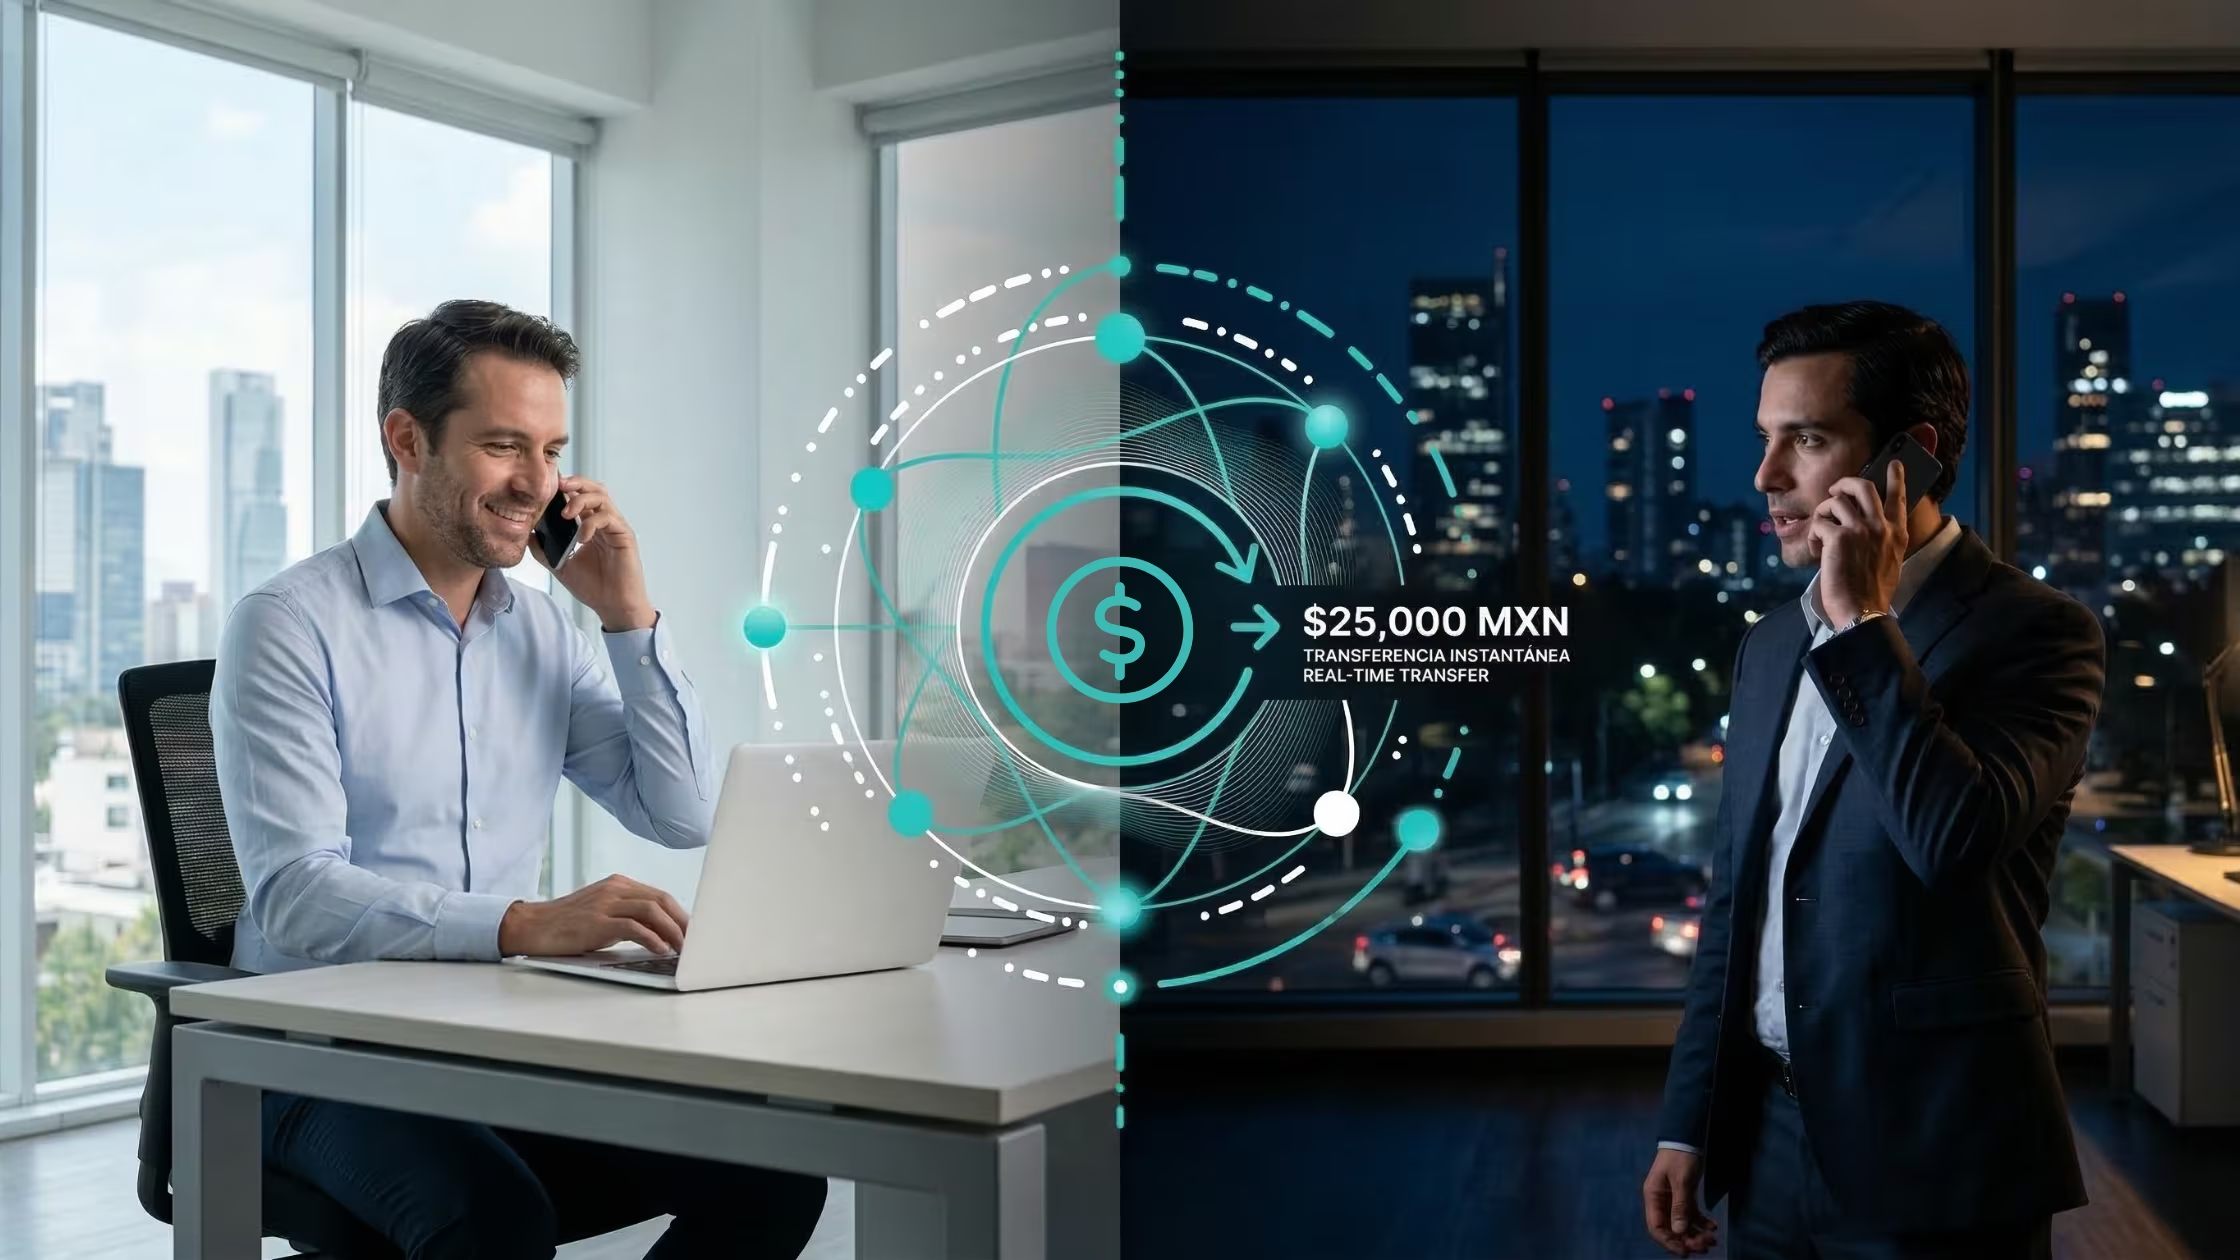
We complete the international transaction cycle by connecting directly to each country’s instant payment systems.
In Colombia, we are the first indirect participant in Bre-B with an API available 24/7/365. In Mexico, we integrate directly with SPEI for real-time settlement. Funds reach local accounts in minutes, not days.
The integration of these three solutions allows a company, for example, to receive a payment in dollars from a U.S. customer, automatically convert it at the current exchange rate, and immediately disburse it in pesos to its local suppliers in Colombia or Mexico—all from a single platform and with full visibility into the process.
Foreign exchange operations in Latin America are evolving from fragmented manual processes to smart, connected infrastructure.
At Cobre, we believe that Latin American companies deserve access to world-class international payment capabilities: instant conversion, transparent costs, and total control. The question is no longer whether to modernize your international operations, but when.
These are transactions in which companies buy, sell, or exchange foreign currencies for international business activities: paying foreign suppliers, receiving export proceeds, or transferring funds between subsidiaries.
According to IAS 21, they are recorded at the exchange rate on the transaction date. At the balance sheet date, monetary items are restated at the closing exchange rate, resulting in exchange differences in profit or loss. Non-monetary items retain their historical exchange rate.
The exchange rate on the transaction date is used for the initial entry, and the closing rate is used to update balances on the balance sheet. The difference between these rates results in a foreign exchange gain or loss that affects your bottom line.
It is a bank account in a currency other than your local currency (for example, a dollar account in Colombia). It allows you to receive international payments, maintain balances in foreign currencies, and optimize the timing of currency conversion for companies with recurring revenue or costs in foreign currency.
International trade in Latin America has grown steadily over the past decade, with countries like Mexico and Colombia positioning themselves as major trade hubs in the region.
However, companies operating cross-border still face significant challenges in their foreign currency transactions: from exchange rate volatility to manual processes that consume valuable hours of financial teams’ time.
Every foreign currency transaction—whether to pay an international supplier or receive export proceeds—involves navigating a complex foreign exchange market with costs that aren’t always transparent.
For many companies, this translates to squeezed margins, tied-up working capital, and exposure to foreign exchange risks that are difficult to mitigate.
This guide explores what foreign currency transactions are, why your company needs them, the main operational challenges you’re likely facing, and how modern payment infrastructure is changing the game for Latin American companies.
Foreign exchange trading refers to transactions in which companies buy, sell, or exchange currencies to conduct international business activities.
We are not talking about speculative trading in the foreign exchange market, but rather about real operational needs: paying a supplier in China, receiving payment for an export in dollars, or transferring funds between subsidiaries in different countries.
Foreign currency transactions directly impact three critical areas of a business:
Foreign trade is the primary driver of foreign exchange transactions.
If you are an importer, every payment order to your international suppliers requires converting your local currency into the corresponding foreign currency. These foreign exchange costs must be carefully managed to maintain your profit margins.
Imagine you import electronic components from Asia: you have to conduct FX transactions to pay in dollars or yuan, and assume the risk of exchange rate fluctuations between the time you quote and when you finally pay.
The impact of foreign currency transactions on your cost structure can be significant if the currency market moves unfavorably during this period.
Exporters face the opposite challenge.
You receive revenue in foreign currency that you need to convert to local currency to cover operating costs, pay payroll, and report results.
The decision of when to make that conversion, considering the subsequent exchange rate valuation, can generate foreign exchange gains or losses that make a significant difference in your margins.
If your company operates in multiple countries, FX transactions are a daily necessity for efficient cash management:
Another alternative for corporate treasury is the use of stablecoins for cross-border transactions or B2B payments. Learn what a stablecoin is, its types, and regulations.
The volatility of average exchange rates poses a real risk to companies with foreign currency exposure.
The Colombian peso can fluctuate between 8% and 12% annually, and the Mexican peso exhibits similar patterns of volatility. This volatility can literally wipe out your operating margins if not managed properly, especially when considering the effects of inflation on purchasing power.
Hedging strategies allow you to lock in future rates in the foreign exchange market, protecting your budgets against exchange rate fluctuations and giving you the financial predictability you need to make strategic decisions with confidence.
However, not all volatility requires long-term hedging instruments. There is a different, more immediate but equally costly exposure: the one that occurs in the hours or days between the moment you decide to make a payment and when you can actually complete it.
This is where locking in the exchange rate at the time of the decision becomes critical.
Unlike traditional hedging instruments that lock in rates for distant future dates, this approach protects trades you’ve already decided to execute but that face inevitable operational delays: internal approvals, settlement cycles, and transaction aggregation.
You are not speculating on future market movements or committing capital long-term; you are simply eliminating the uncertainty of that small but costly time gap between decision and execution. It is tactical hedging for immediate transactions, not a strategy for future exposures, and it becomes a natural complement to your broader foreign exchange risk management tools.
Although currency volatility is a known risk, many mid-sized companies face a more immediate problem: they cannot access the instruments that would allow them to protect themselves.
Financial corporations and traditional banks set requirements that work well for large corporations but prove prohibitive for smaller-scale companies.
The result is a significant gap: companies that fully understand foreign exchange risk and want to protect themselves, but simply do not qualify for the available tools.
Unfortunately, they find themselves in a middle ground where they are too large to ignore the risk, but too small to access traditional foreign exchange market solutions.
One of the most common challenges in foreign exchange transactions is determining the actual cost of your transactions.
The exchange rates you receive do not always reflect the actual rates you will end up paying, which directly affects the valuation of your transactions.
Bank spreads are not visible upfront, and when money passes through domestic intermediaries or correspondent banks, fees accumulate in ways you didn’t anticipate.
Together, these costs can represent between 2% and 5% of the total transaction amount, depending on the route, the currencies involved, and the participating banks.
Traditional international transfers via SWIFT can take between 3 and 5 business days to complete.
This delay has direct implications for your working capital: funds that are "in transit" are not generating value or available for other operations, and foreign currency deposits remain tied up during that period.
Furthermore, when you identify a favorable exchange rate today but your conversion and transfer process takes several days, you will likely miss that window of opportunity.
The closing exchange rate may vary significantly from when you initiated the transaction.
This is precisely the most frustrating liquidity problem: to avoid missing a favorable rate, many companies are forced to bring forward the conversion and keep capital locked up in the target currency until they actually need to make the payment.
But that means tying up funds that could be financing other operations or capitalizing on other opportunities. The alternative is to be able to lock in that favorable rate the moment you identify it, without having to move or reserve a rate until you’re actually ready to execute.
This transforms liquidity management: you no longer have to choose between protecting your rate or maintaining flexibility with your capital.
The typical process for a manual international transfer takes between 20 and 30 minutes: preparing the information in Excel, logging into multiple banking portals, copying data field by field, uploading supporting documentation, requesting approval tokens.
This manual process increases the risk of error in each of your foreign currency transactions.
When these errors occur, the costs of correction include bank investigation fees and additional delays of several days, not to mention the time your team spends resolving the issue.
Each country has its own requirements for foreign exchange transactions.
Navigating these multiple, changing, and sometimes conflicting requirements across jurisdictions represents a significant operational burden, especially for companies without dedicated compliance departments.
Furthermore, the accounting treatment of these transactions under financial reporting standards such as International Financial Reporting Standards (IFRS) adds another layer of complexity, particularly in calculating fair value and the resulting differences between various measurement methods.
Latin American companies have three main options for managing their foreign exchange transactions, each with specific advantages and limitations:
The most common option due to trust and existing banking relationships. Banks act as intermediaries in the foreign exchange market, facilitating access to the currency market. However, they have significant operational limitations:
They offer more competitive spreads for spot transactions and more streamlined processes than banks. Their limitations include:
The latest option on the market, offering clear technological advantages: APIs for integration, cost transparency, and digitized processes. The experience varies by provider in terms of currency coverage, compliance robustness, and quality of support.
The most advanced platforms, such as Cobre’s Cross Border Payments, operate with an architecture that connects multiple global financial infrastructure providers, offering coverage in over 70 countries and 40 currencies.
What sets these modern platforms apart is the combination of operational flexibility—you can use APIs for full automation of international payments or web interfaces for manual operations—with built-in compliance that automatically handles KYC and AML in accordance with each jurisdiction’s regulations.
The result is that you no longer need to establish banking relationships in every country where you operate; you access the global infrastructure through a single integration.
There is a significant gap for mid-sized companies. They are too large for currency exchange firms to handle their volume and operational complexity, yet too small to qualify for the best terms and services offered by corporate banks.
This gap is precisely where modern fintech infrastructure is making the greatest impact.
Mid-sized companies can now access capabilities that were previously reserved only for large corporations: international payment APIs, accelerated settlement, real-time visibility, and unified management of multiple currencies and jurisdictions.
Platforms like Cobre are building infrastructure specifically tailored to the Latin American context, with operations in the region.
The way companies conduct foreign exchange transactions is evolving rapidly in Latin America.
What used to require calling your bank to get a rate quote, waiting for approvals, logging into multiple portals, and waiting days for the conversion and transfer can now be handled through technology platforms designed specifically for corporate FX transactions.
This transformation not only reduces costs: it fundamentally changes companies’ ability to capitalize on favorable timing in conversions, protect margins, and maintain optimal liquidity in their international operations.
Latin American companies conducting foreign currency transactions need an infrastructure that understands the region’s unique characteristics.
At Cobre, we’ve built exactly that: a platform designed for companies operating in and from Colombia and Mexico, integrating cross-border FX capabilities with local payment rails.
We complete the international transaction cycle by connecting directly to each country’s instant payment systems.
In Colombia, we are the first indirect participant in Bre-B with an API available 24/7/365. In Mexico, we integrate directly with SPEI for real-time settlement. Funds reach local accounts in minutes, not days.
The integration of these three solutions allows a company, for example, to receive a payment in dollars from a U.S. customer, automatically convert it at the current exchange rate, and immediately disburse it in pesos to its local suppliers in Colombia or Mexico—all from a single platform and with full visibility into the process.
Foreign exchange operations in Latin America are evolving from fragmented manual processes to smart, connected infrastructure.
At Cobre, we believe that Latin American companies deserve access to world-class international payment capabilities: instant conversion, transparent costs, and total control. The question is no longer whether to modernize your international operations, but when.
These are transactions in which companies buy, sell, or exchange foreign currencies for international business activities: paying foreign suppliers, receiving export proceeds, or transferring funds between subsidiaries.
According to IAS 21, they are recorded at the exchange rate on the transaction date. At the balance sheet date, monetary items are restated at the closing exchange rate, resulting in exchange differences in profit or loss. Non-monetary items retain their historical exchange rate.
The exchange rate on the transaction date is used for the initial entry, and the closing rate is used to update balances on the balance sheet. The difference between these rates results in a foreign exchange gain or loss that affects your bottom line.
It is a bank account in a currency other than your local currency (for example, a dollar account in Colombia). It allows you to receive international payments, maintain balances in foreign currencies, and optimize the timing of currency conversion for companies with recurring revenue or costs in foreign currency.